
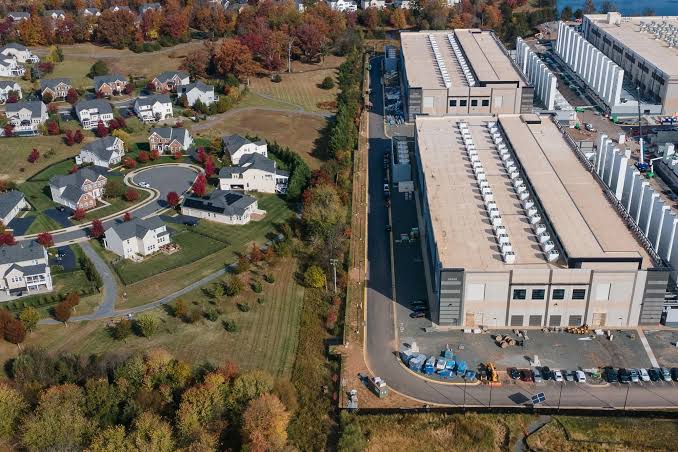
Kenya’s rapid expansion of data-centre infrastructure is exposing a sustainability challenge that extends beyond the availability of land and fibre connectivity: how to measure and disclose the electricity, water, carbon and social impacts of facilities that are becoming increasingly important to the country’s digital economy.
The issue became visible in 2026 when the proposed $1 billion Microsoft-G42 data-centre development in Olkaria encountered delays linked to electricity capacity and payment guarantees. The project, announced in 2024 as a geothermal-powered facility supporting Microsoft Azure’s planned East Africa cloud region, was designed around renewable energy and water-conservation technology. Reuters reported in May that the project had encountered delays over the Kenyan government’s ability to meet requested payment guarantees, while Kenyan officials said discussions were continuing and that the project could be scaled or redesigned.
The episode highlighted a constraint that is becoming harder for African data-centre markets to ignore. Digital infrastructure may be built to international sustainability specifications, but its actual environmental footprint is determined by the physical systems surrounding it: electricity generation, grid capacity, cooling requirements, water availability and the infrastructure needed to connect large facilities to the power system.
Kenya is particularly relevant because it has one of Africa’s most renewable-heavy electricity systems. During the 2024/25 financial year, geothermal accounted for 39.51% of electricity generated, hydropower 24.21%, wind 13.18% and utility-scale solar 3.27%, while electricity imports and thermal generation supplied the remainder. The International Energy Agency has similarly described Kenya as having nearly 90% renewable electricity generation, with geothermal forming the largest component.
That renewable profile has helped make Kenya attractive to data-centre developers. But it does not mean that every additional megawatt of digital demand can be absorbed without consequences. A hyperscale data centre operates continuously, unlike many commercial electricity users whose demand can fluctuate significantly during the day. Large facilities therefore create a different type of load on generation, transmission and distribution infrastructure.
The proposed Microsoft-G42 facility brought that issue into sharp focus because its eventual capacity was expected to reach as much as 1 gigawatt. Reporting at the time of the delays compared that requirement with Kenya’s roughly 3-gigawatt generation system, illustrating the scale of the infrastructure challenge. The alternative is already visible in Tatu City, where Airtel Africa’s Nxtra is developing a 44 MW data centre expected to be commissioned in the first quarter of 2027. The company describes the facility as part of a wider African network designed to support cloud computing, artificial intelligence and enterprise workloads.
The contrast is useful because it shows that Kenya’s data-centre market is not necessarily constrained by demand for digital infrastructure. The more immediate question is how quickly power, transmission, water and other supporting infrastructure can expand alongside it. That makes environmental, social and governance disclosure more consequential. Data-centre operators increasingly report sustainability indicators, but the information available to investors, regulators, lenders and communities is not always directly comparable from one facility to another. A statement that a facility is “green” says little unless the underlying electricity, water and emissions data are defined, measured and reported consistently.
There are already international standards that provide much of the technical foundation. ISO/IEC 30134-2:2026 defines Power Usage Effectiveness, or PUE, as a key performance indicator for measuring how efficiently a data centre uses energy. The standard establishes requirements for measurement, calculation, reporting and interpretation.
Water Usage Effectiveness, or WUE, is separately defined under ISO/IEC 30134-9 as a measure of data-centre water consumption during operation. Carbon Usage Effectiveness, or CUE, provides a corresponding metric for quantifying the carbon emissions associated with data-centre operations. These metrics do not, however, answer every question facing Kenya’s market. PUE can show how efficiently a facility uses electricity, but it does not by itself reveal whether that electricity is placing pressure on a constrained local grid. WUE can measure water consumption, but a consumption number without information about the source and condition of the relevant water basin provides limited information about local water stress.
This distinction is becoming particularly relevant around Olkaria and the wider Naivasha basin. The Microsoft-G42 project was designed to use geothermal energy and incorporate water-conservation technology, but concerns about water availability emerged alongside the debate over the facility’s power requirements. Reporting from the region has highlighted existing pressure on water resources used by communities, agriculture and other economic activities.
A credible Kenyan disclosure framework would therefore need to go beyond publishing a single efficiency ratio. It could require operators to identify the source of electricity, report facility-level energy consumption, disclose PUE and WUE using standardised boundaries, calculate Scope 2 emissions using an appropriate Kenyan electricity factor, and identify the source of cooling water and the relevant catchment or basin conditions.
The quality of the underlying data would matter as much as the number itself. Operators should distinguish between figures that have been directly measured, those calculated using recognised methodologies, estimates based on incomplete data and future projections. That distinction would allow lenders, regulators and communities to understand the level of confidence that should be attached to each disclosure.
Kenya’s emerging sustainability-reporting framework provides an opportunity to build such a system into existing reporting requirements rather than creating an entirely separate regime. ICPAK’s roadmap for the adoption of IFRS Sustainability Disclosure Standards provides for mandatory adoption by public-interest entities from accounting periods beginning on or after January 1, 2027, followed by large non-public-interest entities in 2028 and SMEs in 2029. Readiness assessments are being used ahead of mandatory reporting.
The data-centre sector could therefore develop a sector-specific reporting annex aligned with IFRS S1 and S2 while drawing on the more technical ISO/IEC 30134 metrics. Such an approach would allow investors to compare facilities without requiring operators to create an entirely separate sustainability-reporting architecture.
The international regulatory environment also makes a Kenya-specific approach more relevant. Europe’s 2026 sustainability reforms narrowed the scope of the CSRD and introduced a value-chain cap intended to limit the amount of sustainability information large companies can require from smaller businesses. The European Commission subsequently adopted revised ESRS and a voluntary reporting standard designed to reduce reporting burdens.
That means the assumption that European regulation will automatically force increasingly detailed ESG disclosure throughout African supply chains is less reliable than it once appeared. The more durable drivers may increasingly come from lenders, investors, technology customers, infrastructure partners and domestic regulators.
For Kenya, that creates an opportunity. Rather than waiting for international cloud providers or multinational tenants to determine what constitutes acceptable disclosure, regulators and industry participants could establish a common baseline that reflects the country’s own power and water realities while remaining legible to international capital.
The social and governance dimensions would also need to be incorporated. Large data-centre campuses can involve significant land requirements, infrastructure investment and long-term contractual arrangements. Disclosure could therefore extend to local employment, procurement, skills development, community engagement, land-related impacts, data governance and the ownership or control structures behind major facilities.
Data sovereignty is particularly relevant as cloud computing and artificial intelligence increase demand for locally hosted infrastructure. Kenya’s government has positioned the country as a regional digital gateway, while the recent launch of Digital Realty’s NBO2 data centre in Nairobi was presented as infrastructure supporting cloud providers, financial services, enterprises and internet service providers across East Africa.
The governance question is therefore not limited to where servers are physically located. It also concerns who controls the infrastructure, where critical data is processed, how energy and environmental commitments are verified, and whether the economic benefits associated with rapidly expanding digital infrastructure are captured locally.
A common reporting framework could also improve the quality of project finance. Development-finance institutions, commercial banks and institutional investors increasingly need comparable information when assessing climate and resource risks. A facility that reports its energy, water, emissions and social performance according to consistent definitions would give financiers a stronger basis for assessing operational and transition risks.
For operators, standardisation could also reduce reporting fragmentation. Rather than responding to different sustainability questionnaires from every lender, tenant or investor, a common Kenyan data-centre annex could provide a recognised baseline that can then be mapped to international frameworks. The opportunity is not to create another layer of ESG bureaucracy. It is to make existing disclosure more useful. Kenya already has several pieces of the infrastructure required for such an approach. Its power system has a high renewable share, the country is developing a substantial digital-infrastructure market, ICPAK is implementing IFRS S1 and S2, and the Kenya National Carbon Registry was formally launched in February 2026 following development, testing and institutional validation.
What remains is to connect those systems. The Microsoft-G42 experience illustrates why that matters. The project’s difficulties were not fundamentally about whether geothermal power could provide a lower-carbon electricity source. They exposed the physical and financial limits that emerge when very large digital loads are introduced into an electricity system that must continue serving households, businesses and other industries. Reuters reported that negotiations remained ongoing, meaning the project’s final configuration should not be treated as settled. Meanwhile, projects such as Nxtra’s 44 MW Tatu City facility demonstrate that data-centre development is continuing. The sector is therefore moving forward even as questions around infrastructure capacity and sustainability disclosure remain unresolved.
For Kenya, the policy window is still open. The country can allow each operator to determine its own ESG vocabulary, or it can establish a common framework based on measurable indicators, recognised international standards and local resource conditions. The latter approach would make Kenya’s data-centre market easier to scrutinise without necessarily making it less investable. It could give financiers clearer information, regulators a consistent basis for oversight, operators a common reporting language and communities greater visibility into how major digital facilities use shared resources.
The data-centre boom is likely to continue as demand for cloud computing, artificial intelligence and digital services expands across Africa. The question is no longer simply whether Kenya can attract the infrastructure. It is whether the country can build the transparency needed to understand its real costs and benefits.
If Kenya succeeds, the result could extend beyond its own data-centre market. A locally developed reporting baseline that combines IFRS sustainability disclosures with data-centre-specific measures for energy, water, carbon and resource context could provide a template for other African markets facing the same combination of digital growth, infrastructure constraints and climate risk. The opportunity is therefore bigger than ESG reporting. It is about establishing the information infrastructure required to govern the physical infrastructure of Africa’s digital economy.
Author bio :
Karl Amolo, Sustainability Manager at Urban Canopy Kenya, is an ISO 50001 Lead Auditor and GHG Protocol practitioner completing an MBA thesis on ESG for Kenya’s data-centre sector