
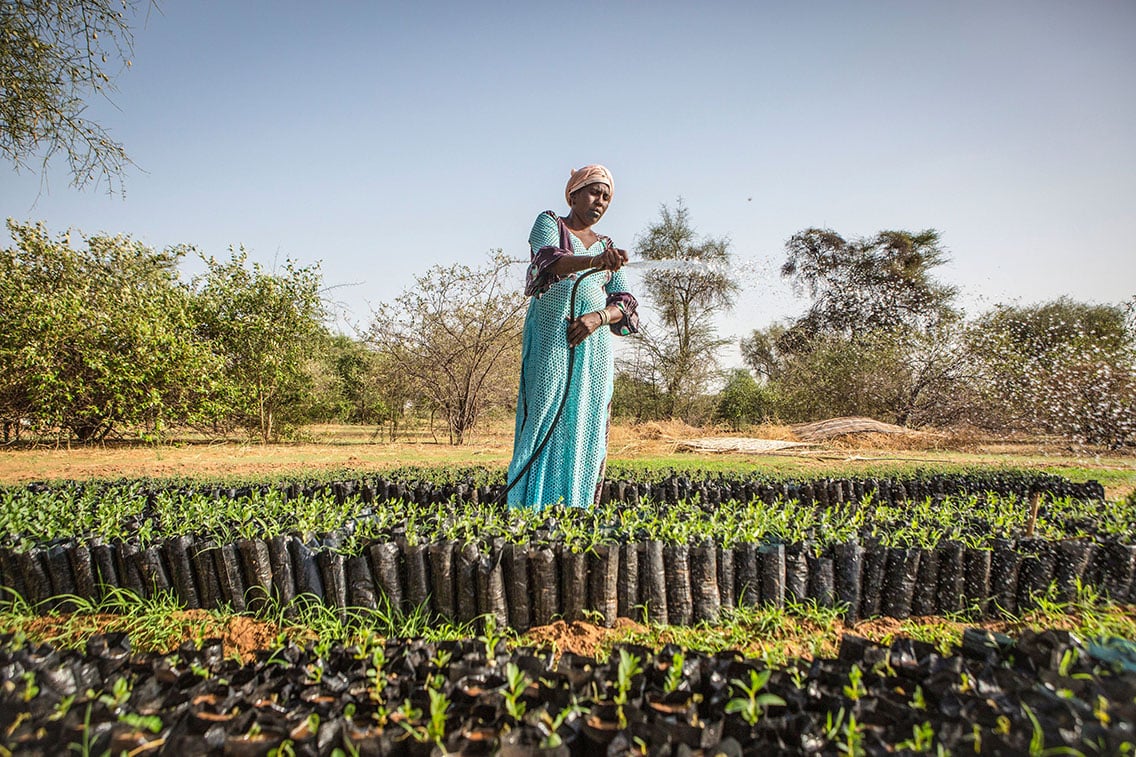
Africa’s forests are receiving less than 1% of global climate finance despite accounting for around one-fifth of the world’s cost-effective mitigation potential, according to the Forest & Climate Leaders’ Partnership’s 2026 Forest Finance Roadmap Progress Report, highlighting a financing gap that is increasingly linked to the continent’s development, fiscal and economic priorities. The report estimates that closing the global forest finance gap will require an additional $66.8 billion a year, while warning that existing mechanisms for carbon markets, public finance, forest-based industries and sovereign debt have yet to operate at the scale required to change the economics of keeping forests standing.
The report, released one year after the Forest Finance Roadmap was launched by the FCLP with Brazil and the United Nations Environment Programme, tracks progress across six areas: jurisdictional REDD+, the Tropical Forests Forever Facility, the sustainable forest bioeconomy, sustainable value-chain finance, targeted public finance and sovereign debt management. Its central finding is that there are signs of movement, but the pace and scale of financing remain well below the level needed to support forest protection while meeting the development needs of forest countries and communities.
For Africa, the financing question is particularly consequential because forests are closely connected to agriculture, water systems, rural employment, biodiversity and the fiscal prospects of countries that depend on natural resources. The report argues that forest countries cannot simply be expected to absorb the economic costs of conservation when cleared land can generate more immediate financial returns than standing forests. That imbalance places the cost of maintaining globally valuable ecosystems disproportionately on countries and communities that also need to expand jobs, incomes and public services.
Jurisdictional REDD+ is one area where financing mechanisms are beginning to develop. Between July 2025 and June 2026, at least $473 million was paid for jurisdictional REDD+ results, with at least 85% coming from public sources. The payments covered at least 86 million tonnes of carbon dioxide equivalent from 12 jurisdictions, while cumulative payments for jurisdictional REDD+ results since 2009 reached at least 646 million tonnes.
The emergence of compliance markets is also creating new potential demand. The report notes that forest carbon units from several standards have become eligible for purchase under the International Civil Aviation Organization’s Carbon Offsetting and Reduction Scheme for International Aviation, or CORSIA. It also records a significant potential supply-demand imbalance: the International Air Transport Association estimates first-phase CORSIA offsetting requirements at 213 million tonnes of carbon dioxide, compared with 38 million tonnes of eligible units currently available.
For African forest countries, however, access to these markets will depend on more than the existence of forest carbon. Governments need functioning regulatory systems, credible measurement and verification arrangements and clear rules governing the authorisation and accounting of international carbon transfers. The report specifically identifies carbon-market rules, CORSIA implementation and predictable demand as areas requiring further development.
The Congo Basin illustrates the scale of the financing challenge. Donors had provided more than $1.9 billion under the earlier Congo Basin financing commitment between 2021 and 2024, while a renewed commitment made at COP30 seeks to raise more than $2.5 billion over the following five years. The renewed effort involves Central African countries alongside Germany, Belgium, France, Norway, the United Kingdom, the African Development Bank, the World Bank, the European Commission and climate-finance institutions.
Such financing is important because forest protection is not an isolated environmental expenditure. In Central Africa, forests underpin water regulation, agricultural systems, livelihoods and local economic activity. The report’s emphasis on locally led action and tenure rights also reflects a broader financing issue: money directed towards forests needs institutions capable of reaching communities that manage and depend on forest landscapes.
The sustainable forest bioeconomy offers another route for connecting conservation with economic value. Globally, certified forest products attracted $2.3 billion in private finance in 2023, while multilateral development banks, development finance institutions and climate funds mobilised at least $1.73 billion in 2025/26, including approximately $1.16 billion in private capital. The report estimates that sustainable forest bioeconomy activities could have capital mobilisation potential of about $15 billion a year.
Kenya is among the African countries highlighted in the report. Its Industrial Wood Sector Vision 2050 estimates an investment requirement of about KSh176 billion, equivalent to roughly $1.36 billion, for commercial tree growing and processing. During the reporting period, at least $229 million in new external finance was approved for forest- and landscape-based economic development, principally through a $200 million World Bank operation and a $29.2 million Green Climate Fund grant for the Lake Region. Kenya also increased its forestry budget by about $38.7 million in the 2025/26 financial year.
The Kenyan case demonstrates why forest finance is increasingly being framed as an industrial and economic question. Investment in plantations, smallholder tree growing and wood processing can create opportunities for value addition, while infrastructure, skills and market development determine whether those opportunities translate into domestic economic activity. The report describes Kenya’s strategy as an effort to connect forest resources with a broader forest-to-frame value chain rather than treating forestry solely as a conservation activity.
Public finance remains another critical part of the equation. In Ethiopia, land degradation is estimated in the report to cost $4.3 billion annually through reduced agricultural productivity and lost ecosystem services. The country’s Green Legacy and Landscape Restoration Fund receives between 0.5% and 1% of the annual national budget, equivalent to approximately $40 million to $80 million a year, and has helped underpin larger concessional and co-financing flows from international partners.
The report also puts forests closer to the centre of sovereign debt discussions. Developing countries face growing debt-service pressures, with the median share of government revenues allocated to external public and publicly guaranteed debt service reaching 9.9% in 2024, the highest level since 2004. Against that backdrop, the report identifies debt conversions, sustainability-linked sovereign instruments and climate-related debt analysis as potential mechanisms for aligning fiscal management with forest and biodiversity outcomes.
Africa already has an example of this approach. Côte d’Ivoire launched what the report describes as Africa’s first Sustainability-Linked Finance Framework and secured a €433 million sustainability-linked sovereign loan, with borrowing costs linked to measurable targets covering renewable energy, deforestation prevention and reforestation. The transaction was supported by a combined World Bank and Multilateral Investment Guarantee Agency guarantee.
Uganda is taking a different approach by piloting a framework that incorporates adaptation and forest-resilience outcomes into sovereign debt sustainability analysis and credit ratings. The approach links investment in agroforestry and ecosystem restoration with indicators such as economic growth, export stability, fiscal performance and sovereign creditworthiness.
These developments point to a broader change in how forest finance is being considered. Rather than treating forests exclusively as recipients of environmental funding, governments and financial institutions are beginning to examine how natural assets affect economic resilience, agricultural productivity, exports, public finances and the cost of capital. The report calls for closer coordination between finance ministries, sovereign debt authorities, forest agencies and development finance institutions so that forests and biodiversity can be incorporated into wider economic and fiscal strategies.
For Africa, the challenge will be converting these mechanisms from individual transactions and pilots into durable financing systems. That will require credible forest data, stronger institutions, transparent carbon accounting, functioning local markets and financial structures capable of sharing risk between governments, development institutions and private investors. The report itself cautions that its six financing indicators are not directly comparable or additive, underscoring the need for better measurement of how much capital is actually reaching forest economies.
 The Forest Finance Roadmap therefore presents a financing problem that extends well beyond conservation. Africa’s forests sit within the continent’s agricultural systems, water resources, rural economies and natural-resource base, while governments face tight fiscal space and rising demands for infrastructure and development spending. Closing the forest finance gap will consequently depend on whether international and domestic financial systems can assign greater economic value to standing forests while creating investable pathways for the communities, businesses and governments responsible for managing them.