
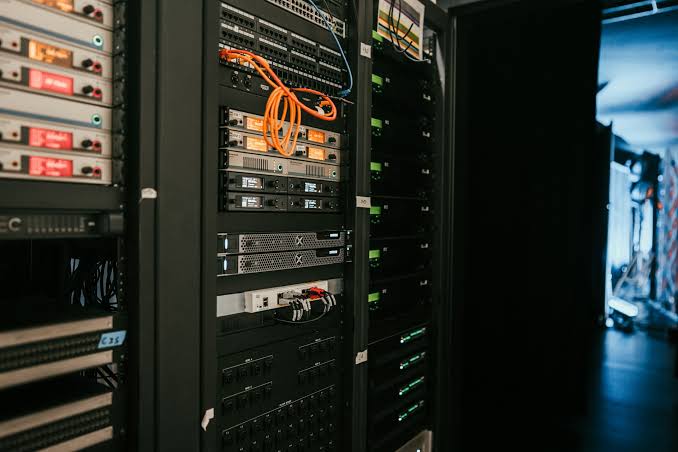
Kenya’s expanding digital infrastructure market is bringing a new sustainability challenge into focus as investment in data centres, cloud computing and artificial intelligence increases demand for electricity, water and supporting infrastructure. The development is significant for Kenya’s ambition to strengthen its position as a regional technology hub, but it also raises questions about whether the country’s energy systems, environmental safeguards and investment frameworks can accommodate the resource requirements of a rapidly growing digital economy.
The investment conversation, reflected in the growing focus on African technology infrastructure, comes as governments and businesses across the continent seek to expand digital services, improve connectivity and attract capital into technology-intensive industries. For Kenya, whose digital economy supports financial services, telecommunications, public administration and a growing technology sector, the next phase of infrastructure development will depend not only on connectivity and computing capacity but also on the reliability and sustainability of the systems supporting them.
Data centres are central to this transition. They provide the computing, storage and network capacity required for digital payments, cloud services, enterprise platforms and increasingly AI-enabled applications. However, their operations are resource-intensive. Electricity is required to power servers and cooling systems, while water may be used directly or indirectly in cooling processes. The construction of facilities also creates demand for land, building materials, transmission infrastructure and backup power systems.
Read also: https://www.investafrica.com/invest-africa-events-calendar
According to the International Energy Agency, electricity consumption from data centres, artificial intelligence and cryptocurrency could increase substantially through the second half of the decade, although the pace will depend on technology efficiency, deployment patterns and demand growth. For emerging digital markets such as Kenya, the implications extend beyond the facilities themselves to the capacity of national grids, the cost of electricity and the availability of infrastructure capable of supporting large, continuous loads.
Kenya’s electricity system has a substantial renewable energy base, with geothermal, hydro, wind and solar contributing to generation. This provides an opportunity for digital infrastructure investors to align operations with lower-carbon electricity. Yet renewable generation alone does not resolve the sustainability challenge. Grid congestion, transmission capacity, power quality, storage and the timing of electricity supply all influence whether data centres can operate reliably while maintaining a lower emissions profile.
The distinction matters because digital infrastructure requires continuous power. Where grid reliability is insufficient, operators may rely on diesel generators or other backup systems, adding operating costs and emissions. The long-term sustainability of investment will therefore depend partly on whether new digital facilities are integrated into electricity planning rather than treated as isolated commercial developments.
Water presents another consideration. Kenya faces uneven water availability, with urban growth, agriculture, industry and climate variability placing pressure on supply systems. Data centre cooling requirements could add to these pressures, particularly where facilities are located in areas already facing competition for water resources. The scale of this impact will vary according to cooling technology, facility design, water sourcing and operational efficiency.
For county governments and utilities, this creates a planning issue that extends beyond attracting investment. Decisions on land allocation, water permits, power connections and environmental approvals can influence whether digital infrastructure contributes to local economic development without placing additional strain on public services.
The economic case for investment remains substantial. Digital infrastructure can support financial inclusion, regional cloud services, business productivity, digital trade and the delivery of public services. It can also create demand for construction, engineering, cybersecurity, facilities management and technical skills. Kenya’s position as a regional technology and financial services centre gives it an incentive to attract infrastructure capable of serving domestic and neighbouring markets.
However, the distribution of these benefits is not automatic. Data centres are capital-intensive and can operate with relatively limited direct employment once construction is complete. Their wider contribution will depend on local procurement, skills development, technology partnerships and the extent to which domestic businesses can access the services they provide.
Financing structures will also influence the development pathway. Digital infrastructure projects require significant upfront capital, long-term power arrangements and confidence in regulatory stability. Investors may assess electricity prices, foreign exchange exposure, land and permitting processes, connectivity and the availability of reliable infrastructure. At the same time, sustainability requirements are becoming more relevant to financing decisions, particularly where lenders and institutional investors assess environmental risks and operational resilience.
Kenya’s policy environment will therefore need to connect digital investment with energy planning, climate commitments and environmental governance. This includes clearer expectations on energy efficiency, renewable electricity procurement, water-use reporting, electronic waste management and environmental impact assessment. Transparent reporting could help regulators, investors and communities understand the resource footprint of major facilities and assess whether mitigation measures are being implemented.
Electronic waste is another part of the equation. Servers, batteries, cooling equipment and other components have finite operating lives, creating requirements for repair, reuse, recycling and responsible disposal. As digital infrastructure expands, effective waste-management systems will become increasingly important to prevent the environmental costs of technological growth from shifting to municipalities and informal waste workers.
The regional dimension is equally relevant. Kenya’s digital infrastructure can support services across East Africa, where demand for cloud computing, digital payments and online public services continues to develop. But regional competitiveness will increasingly depend on more than the availability of data storage and connectivity. Power reliability, sustainable cooling, regulatory predictability and the ability to manage environmental risks will form part of the investment proposition.
For African economies, the broader issue is how to ensure that digitalisation strengthens productive capacity without creating new infrastructure vulnerabilities. Electricity and water are already essential inputs for households, agriculture, manufacturing and public services. Large new users must be incorporated into planning processes that account for competing demand, climate exposure and the cost of expanding networks.
Kenya’s digital infrastructure investment therefore presents both an economic opportunity and a governance test. The ability to attract capital will matter, but so will the quality of the infrastructure, the transparency of resource use and the extent to which investment supports domestic capabilities. As AI and cloud services become more embedded in economic activity, the sustainability of the digital economy will increasingly depend on decisions made today about power, water, financing and public accountability.