
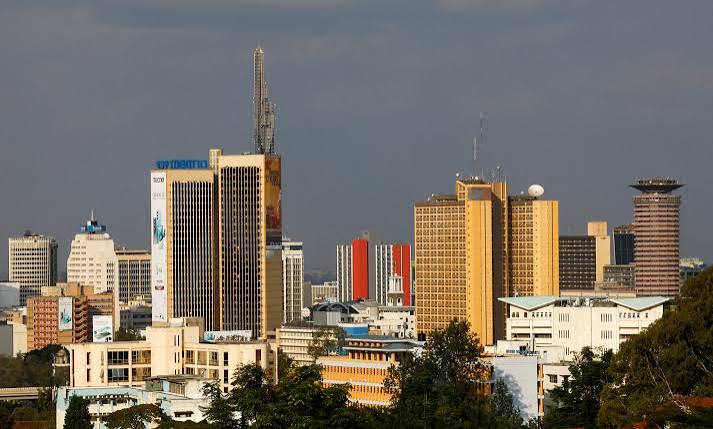
Kenya has begun deploying the KSh340 billion ($2.62 billion) seed capital of its National Infrastructure Fund, initially through purchases of domestic government bonds, as the government seeks to finance infrastructure while limiting additional pressure on public debt and attract private capital into commercially viable projects. The fund, which began buying bonds in July, is expected to deploy its full capital by June 2027 and eventually mobilise KSh3.6 trillion over the next decade through co-investments and debt.
The launch comes as Kenya faces a widening gap between its infrastructure requirements and the fiscal capacity available to finance them. Government debt repayments consume about 40% of public revenue, according to the fund’s Chief Executive James Mworia, while demand for investment in energy, transport, logistics, water, agriculture and digital infrastructure continues to grow. The government has therefore been looking for financing structures that can support development without relying entirely on additional sovereign borrowing.
According to Reuters, the infrastructure fund is initially using its capital to purchase domestic government securities, a move intended to increase liquidity in the financial system and potentially encourage commercial banks to lend more to businesses and households. Kenyan banks are among the largest holders of domestic government securities and have often preferred lending to the government over private-sector borrowers because of the comparatively lower risk associated with sovereign debt.
The strategy places the fund at an unusual intersection between public finance and private capital markets. Rather than immediately directing the entire seed allocation into physical infrastructure, the vehicle is using part of its capital to participate in the domestic bond market while building the investment capacity required to finance projects directly and alongside other investors.
At KSh340 billion, the fund’s planned investment is equivalent to roughly a third of Kenya’s domestic borrowing target for the financial year ending June 2027. Its bond portfolio is expected to generate about KSh42 billion annually, according to Mworia, providing a potential source of income that can support further investment and help the fund attract additional capital.
The government capitalised the fund using proceeds from the privatisation of Kenya Pipeline Company and the sale of part of its stake in telecommunications operator Safaricom. The structure reflects a broader effort to convert existing state assets into capital that can be deployed into infrastructure and other productive investments rather than relying solely on new borrowing.
The fund is expected to focus on commercially viable projects in energy, transport and logistics, information and communications technology, water and agriculture. These sectors are central to Kenya’s economic competitiveness because infrastructure constraints can increase the cost of moving goods, restrict access to markets, affect industrial productivity and place pressure on household and business costs.
Energy is particularly important to the model. Kenya has expanded its renewable electricity generation and private investment in distributed energy, but transmission capacity, reliability, industrial power demand and the financing of large infrastructure projects remain important constraints. An infrastructure investment vehicle capable of bringing together public capital, commercial lenders and institutional investors could provide an additional route for financing projects that require substantial upfront investment and have long operating lives.
Water and agriculture present a similar financing challenge. Investments in irrigation, water supply, storage and logistics can generate broad economic benefits but may not always provide the immediate commercial returns required by conventional private finance. The fund’s ability to structure investments around viable revenue streams, risk-sharing mechanisms and co-investment arrangements will therefore be important in determining which projects can move from proposals to financial close.
The government is also considering using the fund to take a stake in a refinery being developed by Nigerian industrialist Aliko Dangote in Lamu, although the size of any potential investment has not been disclosed. The proposed participation illustrates the scale of industrial infrastructure that Kenya may seek to support through the new financing model, while also linking the fund to wider regional ambitions around energy security, logistics and industrial development.
For Kenya, however, the effectiveness of the model will depend on more than the amount of capital available. Infrastructure projects require preparation, credible financial structures, environmental and social safeguards, predictable regulation and sufficient demand to support their revenues over time. The distinction between capital mobilisation and capital deployment will therefore be significant: a large fund does not automatically translate into a large pipeline of bankable projects.
The sustainability dimension is similarly tied to investment quality rather than labels. Energy, water, transport and agricultural projects can shape emissions, resource use, climate resilience and community outcomes for decades. For an infrastructure fund operating at national scale, environmental and social considerations are consequently part of financial risk management, particularly where projects depend on land, water resources, public infrastructure or long-term government commitments.
The fund’s reliance on co-investment also reflects a wider challenge facing African economies. Across the continent, governments face substantial infrastructure deficits at the same time as debt-service costs, currency risks and high borrowing costs constrain public investment. Development finance institutions, pension funds, insurers, commercial banks and international investors are increasingly expected to provide capital alongside governments, but many projects still struggle to reach financial close because of weak preparation, uncertain revenues or perceived country and currency risks.
Kenya’s approach is therefore relevant beyond its borders. If public seed capital can be used to reduce investment barriers, prepare projects and bring private investors into infrastructure financing, similar structures could offer other African economies a way to stretch limited fiscal resources. The challenge is ensuring that such vehicles complement rather than obscure public debt, maintain transparent investment criteria and direct capital towards projects with measurable economic and development value.
For domestic financial markets, the fund could also influence the balance between sovereign and private sector financing. If its bond purchases increase liquidity and banks subsequently expand lending to businesses, the effect could extend beyond infrastructure into wider private investment. But the transmission from government securities purchases to productive lending will depend on banks’ assessment of credit risk, demand for loans, interest rates and broader economic conditions.
The fund’s longer term target is ambitious. Mworia said it aims to mobilise KSh3.6 trillion over the next decade through co-investments and debt, substantially exceeding the initial government contribution. Achieving that level of mobilisation would require sustained investor confidence, a credible pipeline and institutional capacity to structure projects that can withstand commercial, environmental and regulatory scrutiny.
That makes the initial bond purchases more than a portfolio decision. They are the first step in testing whether state-backed capital can be transformed into a broader financing platform without reproducing the fiscal pressures that helped create the need for it.
For Africa, where infrastructure investment needs remain substantial while governments confront tighter fiscal conditions, the underlying question is increasingly how to make scarce public capital work harder. Kenya’s National Infrastructure Fund offers one answer: use public capital not simply to build infrastructure directly, but to participate in financial markets, develop investable projects and bring additional pools of capital into the development process.
The outcome will ultimately depend on whether the fund can turn that architecture into productive infrastructure while maintaining financial discipline and public accountability. Its first bond purchases provide an early indication of the model; the more consequential test will come as the fund moves from securities into projects, partnerships and long-term investments across Kenya’s economy.