
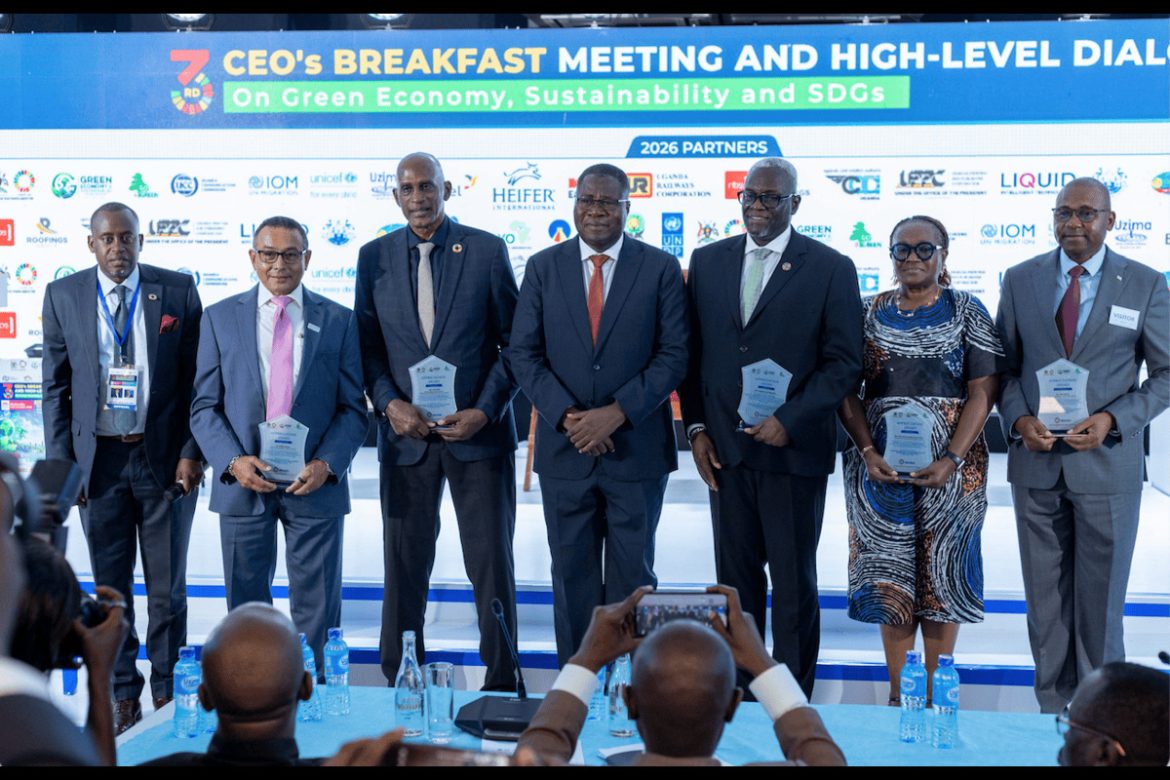
Equity Bank Uganda has allocated approximately KSh1.21 billion in green loans to support climate-related investments, as the lender expands financing for renewable energy, clean-energy technologies and climate-smart agriculture amid growing calls for private capital to accelerate Uganda’s green economy transition.
The bank has also supported the sale of 157,035 clean-energy products, partnered with 18 clean-energy implementing organisations and contributed to planting 96,638 trees over the past three years, according to Managing Director Gift Shoko. The figures highlight the role commercial banks can play in connecting climate and sustainability objectives with financing for households, farmers and businesses.
Shoko presented the bank’s sustainability efforts at the third CEOs’ Breakfast Meeting and High-Level Dialogue on Green Economy, Sustainable Development Goals (SDGs) and Sustainability, held on 14 October 2026 at the UNICEF Conference Centre in Mbuya, Kampala. The meeting, themed “Accelerating Uganda’s Green Economy Transition Through Digital Transformation”, brought together government officials, financial institutions, development partners and private-sector representatives to discuss how investment and technology could support greener economic growth.
“The question is no longer whether Uganda can afford to invest in sustainability. The question is whether we can afford not to,” Shoko said.
His remarks reflected a broader debate about the financing required to make climate action commercially viable and accessible. Renewable energy systems, cleaner cooking technologies, climate-resilient agricultural practices and resource-efficient production can require upfront investment, even where they offer lower operating costs or reduce exposure to climate risks over time. Access to suitable financing can therefore influence whether households and enterprises adopt these solutions.
For commercial lenders, green finance provides an opportunity to direct capital towards investments that support environmental objectives while serving customers’ business and household needs. However, the impact of such lending depends on the affordability of credit, the performance of financed technologies and the ability of borrowers to generate sufficient returns or savings to meet repayment obligations.
Equity Bank Uganda has also linked its sustainability ambitions to a wider regional financing initiative. Equity Group and the International Fund for Agricultural Development (IFAD) launched a US$200 million Africa Rural Climate Adaptation Finance Mechanism in September 2026 to support smallholder farmers and rural enterprises across East Africa. The 12-year programme is designed to expand access to climate-adaptation finance and strengthen the resilience of agricultural value chains.
According to the figures supplied for the initiative, Uganda is expected to receive approximately 25% of the funding, equivalent to about US$50 million. The broader mechanism is intended to reach smallholder producers and micro, small and medium-sized enterprises in Uganda, Kenya, Tanzania and Rwanda. Its financing structure combines lending capital with technical assistance, with the objective of helping farmers and rural businesses invest in adaptation measures and strengthen their ability to withstand climate-related shocks.
For Uganda’s agricultural sector, access to climate finance can support investments in more resilient production systems, water management, improved farm practices and value addition. Smallholder farmers often face difficulty obtaining loans for investments whose benefits depend on seasonal harvests, market prices and increasingly variable weather conditions. Financing designed around these realities could help bridge the gap between climate-adaptation needs and the commercial requirements of lending institutions.
The effectiveness of such programmes will depend on how funds reach businesses and farming communities. Loan eligibility, repayment schedules, technical support and the availability of appropriate agricultural technologies can all influence uptake. Monitoring will also be important to establish whether financing improves productivity and resilience, rather than simply increasing the volume of credit distributed.
Beyond agriculture, Equity Bank Uganda has supported the adoption of clean-energy products through partnerships with 18 implementing organisations. The reported sale of 157,035 products indicates the scale of distribution activity, although the figures provided do not specify the breakdown by technology or the extent to which each product remains in use. Access to clean-energy solutions can reduce reliance on more polluting fuels, but lasting benefits depend on affordability, product quality, maintenance and reliable supply chains.
The bank’s tree-planting activities form another component of its sustainability programme. Over the past three years, it has contributed to planting 96,638 trees, while its Green Schools Programme is targeting 50,000 trees across 25 schools in 10 districts by the end of 2026. The longer-term target is to reach 200,000 trees by 2027.
Among the initiatives reported are the planting of approximately 3,500 trees at Nakanyonyi Secondary School in Mukono, 1,500 at Kyasanku Hill College in Mpigi and 1,000 at St. Julian Secondary School in Wakiso. Busoga College Mwiri has also seen more than 43,000 indigenous trees planted across its hill slopes, according to the supplied information.
Tree planting can contribute to restoring degraded landscapes and supporting biodiversity, but environmental outcomes depend on more than the number of seedlings planted. Species selection, survival rates, maintenance and the suitability of planting sites determine whether such initiatives deliver lasting benefits. Monitoring tree survival over time would provide a clearer indication of the programme’s contribution to restoration and climate resilience.
Equity Bank Uganda has also directed resources towards youth development and financial inclusion. Under the Young Africa Works framework, more than 100,000 young people have received training, while financial literacy and capacity-building initiatives continue to target women and young people. These programmes connect sustainability with the broader challenge of expanding economic opportunity, particularly for groups that may face barriers to finance, skills development and formal employment.
The meeting’s discussions highlighted the need to strengthen public-private partnerships and expand the use of technology to improve energy management, widen access to clean energy and scale climate-smart agriculture. Digital tools can help financial institutions assess borrowers, distribute products and monitor transactions, while agricultural technologies and data services may improve decision-making for farmers. Their value will depend on affordability, connectivity, digital skills and the ability to serve rural communities that remain underserved.
Speaker of Parliament Jacob Markson Oboth, who attended as keynote speaker and guest of honour, joined participants in calling for sustainability commitments to be translated into practical regulations, investment and implementation. The emphasis on public-private cooperation reflects the fact that green finance depends on more than the availability of bank lending. Government policies, infrastructure, market incentives and clear standards can influence the risks and returns associated with sustainable investments.
For financial institutions, this creates a need to balance environmental priorities with sound credit decisions. Lending for clean energy and climate adaptation must be supported by appropriate risk assessment, credible information and repayment structures suited to customers’ cash flows. Development partners can help address some financing and technical barriers, but long-term expansion will require business models that remain viable beyond individual funding programmes.
Equity Bank Uganda’s reported green-loan allocation and clean-energy activities illustrate how commercial finance can support parts of the country’s transition towards a greener economy. The next challenge is determining how effectively these interventions reduce costs, strengthen resilience and create economic opportunities for households and enterprises.
As Uganda seeks to attract more private investment into sustainable development, the success of its green transition will depend on whether finance reaches projects with demonstrable benefits and whether those investments can be maintained over time. Converting climate commitments into measurable outcomes will require collaboration among lenders, government, businesses and development partners, alongside transparent reporting on the results achieved.