
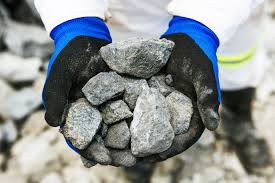
African countries seeking to process more of their mineral resources at home are facing a major constraint: the availability and cost of reliable electricity. Guinea’s ambitions to expand alumina refining and the difficulties confronting South Africa’s ferrochrome industry illustrate how power shortages and high energy costs can undermine investment in mineral processing, limiting the continent’s ability to capture more value from its natural resources. According to Reuters, the electricity requirements of proposed industrial projects in Guinea could far exceed the country’s current generation capacity, highlighting the scale of the infrastructure investment needed to support Africa’s mineral value-addition agenda.
The issue comes as governments across the continent seek to move beyond exporting unprocessed minerals towards domestic refining, processing and manufacturing. The strategy is intended to increase export earnings, create industrial jobs and strengthen links between mining and other parts of the economy. However, processing minerals requires more than access to deposits and international investment. Reliable electricity, transport infrastructure, water supplies and predictable regulation are essential to making industrial operations commercially viable.
Guinea illustrates the scale of the challenge. The country is a major producer of bauxite, the principal raw material used to manufacture alumina, an intermediate product in aluminium production. Expanding domestic refining would allow Guinea to capture more of the value generated between mineral extraction and the manufacture of finished products. Yet alumina refineries require substantial and continuous energy supplies, making electricity availability a central consideration in investment decisions.
According to the Reuters report published on October 19, Guinea generates approximately 1,000 megawatts of electricity, while its industrial ambitions could require between 5,000 and 10,000 megawatts. The gap indicates that developing a larger processing industry would require a significant expansion of generation capacity, alongside investment in transmission and distribution infrastructure.
The financing implications are substantial. Power projects require considerable upfront capital and can take years to develop, while industrial investors need confidence that electricity will be available at competitive prices over the life of their operations. If generation and grid infrastructure lag behind industrial plans, projects may be delayed, scaled back or supplied through dedicated power arrangements that increase costs and limit the benefits available to the wider economy.
The problem is not confined to West Africa. South Africa’s ferrochrome industry has also faced pressure from high electricity costs, illustrating how energy pricing can affect the competitiveness of established mineral-processing operations. Ferrochrome, an important input in stainless steel production, depends on energy-intensive smelting processes. Where electricity becomes too expensive, producers can struggle to compete with international suppliers, placing pressure on industrial employment, exports and associated supply chains.
These examples expose a wider tension in Africa’s industrialisation strategy. Governments want mineral wealth to support domestic production, but energy systems in several markets remain constrained by insufficient generation, ageing infrastructure, financing difficulties or high operating costs. Expanding mineral processing without addressing those constraints risks creating industrial capacity that is difficult to operate profitably.
For public finances, the choices are complex. Governments may need to invest in electricity generation and networks, provide guarantees to attract private capital or negotiate power arrangements with large industrial consumers. Such interventions can help unlock investment, but they also create fiscal and governance risks if projects require sustained public support or if electricity costs are shifted onto households and other businesses. The challenge is to expand supply without creating obligations that weaken public budgets or undermine the financial viability of utilities.
The energy requirements of mineral processing also raise questions about the structure of Africa’s power transition. Renewable energy, hydropower, natural gas, storage and grid upgrades may all contribute to electricity supply, depending on national resources and system requirements. The appropriate mix will differ across countries, but industrial development requires power that is not only available at scale but also dependable and affordable.
Renewable generation can offer opportunities to diversify electricity supply and reduce exposure to volatile fossil fuel prices. However, variable solar and wind output may require complementary investments in storage, transmission, flexible generation and system management to meet the continuous power needs of energy-intensive industries. Hydropower can provide substantial electricity in some markets, although output may be exposed to changing rainfall patterns and drought. These considerations make integrated energy planning important when governments assess new processing capacity.
For mineral producing countries, the objective is therefore not simply to increase electricity generation, but to coordinate energy investments with realistic industrial demand. A refinery or smelter can anchor additional infrastructure investment, but the economic case depends on the cost of supplying power, the expected value of processed output and the ability to maintain production under changing market conditions. Governments and investors need to assess these factors together rather than treating mining, industrial policy and electricity planning as separate agendas.
The stakes extend to employment and local business development. Domestic processing can create demand for engineering services, transport, maintenance, equipment suppliers and technical skills that are not generated to the same extent by exporting raw materials alone. Yet these benefits depend on whether local firms can enter supply chains and whether workers have access to the skills required by industrial operations. If processing projects rely heavily on imported services and dedicated infrastructure, the wider economic gains may be more limited.
There is also a regional dimension. Countries with substantial mineral deposits do not always have the same capacity to finance and operate energy infrastructure, while cross-border electricity trade remains uneven across African markets. Regional power pools and interconnected grids could, where technically and commercially feasible, help broaden access to electricity and spread infrastructure costs across several markets. However, cross-border arrangements require investment in transmission, coordinated regulation and agreements on pricing and supply security.
The investment environment will also influence whether mineral-processing ambitions translate into projects. Mining and industrial investors assess electricity tariffs alongside transport costs, taxation, licensing conditions, access to finance and political and regulatory risks. A country with significant mineral reserves may still struggle to attract processing investment if electricity costs make production uncompetitive. Conversely, reliable power and clear rules can strengthen the case for locating more of the value chain near the source of the resource.
The environmental implications of this expansion will depend partly on how additional electricity is generated and how industrial facilities manage their resource use. Processing minerals can increase emissions, water consumption and local pollution if plants operate with inefficient equipment or rely on high-emission energy sources. Strong environmental regulation, credible monitoring and clear requirements for water management and waste disposal will therefore be important in determining whether industrial expansion delivers durable economic benefits without creating excessive costs for surrounding communities.
For Africa, the debate is increasingly about the conditions required to turn mineral wealth into productive capacity. Exporting raw materials can generate foreign exchange and government revenue, but domestic processing offers opportunities to expand manufacturing, develop technical expertise and strengthen local supply chains. Those opportunities are not automatic: they depend on infrastructure, electricity pricing, access to capital, market demand and the ability of firms to operate competitively.
Guinea’s projected electricity requirements and South Africa’s experience in ferrochrome production underline the need to align industrial policy with power-sector planning. Governments that commit to mineral processing without a credible strategy for electricity supply risk creating a gap between investment ambitions and operational reality. Those that coordinate generation, grid infrastructure, industrial demand and environmental oversight may be better placed to capture more value from their resources.
The test for Africa’s mineral value-addition agenda will be whether countries can build energy systems that support competitive industry while maintaining affordable electricity for households and other productive sectors. Without that foundation, the push to process more minerals domestically could remain constrained by the same infrastructure bottleneck that has limited broader industrial development across parts of the continent.