
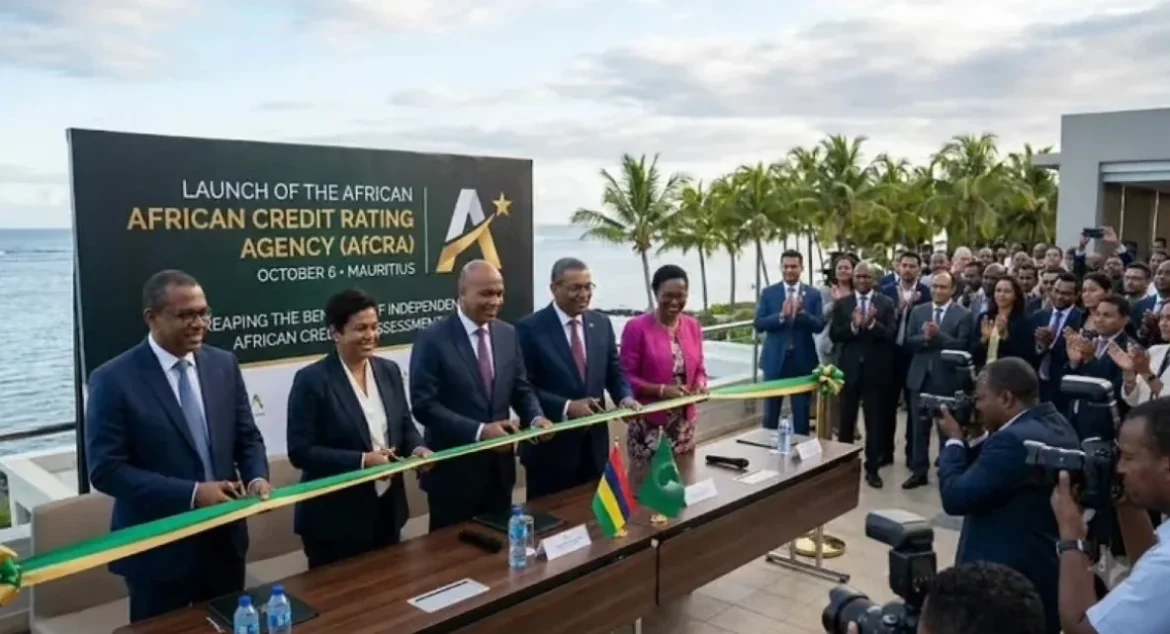
The African Union’s launch of the Africa Credit Rating Agency (AfCRA) has brought the continent’s cost of capital into sharper focus, with African officials arguing that sovereign credit assessments can have significant consequences for borrowing costs, access to international markets and the ability of governments to finance long-term development. The agency, formally launched through the African Peer Review Mechanism in September, is intended to provide an additional source of sovereign credit analysis rooted in African economic conditions and data, at a time when high financing costs are constraining investment across the continent.
Credit ratings influence how investors price sovereign debt and, consequently, how much governments pay to raise financing. Africanews reported that the African Union sees the existing system as insufficiently reflective of local economic conditions and that the resulting risk premium contributes to higher borrowing costs for African states. Dr Misheck Mutize, an adviser to the African Union on credit rating agencies who has been involved in the development of AfCRA, said the agency is intended to strengthen the information available to investors when assessing African economies.
The issue is particularly relevant to sustainable development because the cost of capital affects whether governments and businesses can finance infrastructure over long periods. Roads, electricity networks, water systems, renewable-energy projects and climate-resilience infrastructure often require substantial upfront investment and generate returns over many years. When financing costs rise, projects can become more expensive to structure, public debt-service obligations can consume a larger share of government revenue, and fewer investments may meet the financial thresholds required by private investors.
For African governments, the timing is significant. Many economies are already managing elevated debt-service requirements while seeking additional capital for energy access, transport infrastructure, healthcare, water and sanitation, industrial development and climate adaptation. The African Union’s wider development framework places economic integration and sustainable development at the centre of the continent’s long-term agenda, making access to affordable and predictable finance an important part of translating those objectives into infrastructure and productive investment.
The creation of AfCRA does not, however, by itself change the underlying creditworthiness of individual countries or automatically lower their borrowing costs. Its significance will depend on the quality, independence and credibility of its assessments, as well as whether international and domestic investors incorporate the additional analysis into their investment decisions. Credit-rating markets ultimately depend on investor confidence in methodologies, governance, transparency and the consistency of ratings across jurisdictions.
That distinction is important because Africa’s financing challenge extends beyond how the continent is perceived by external investors. Fiscal performance, foreign-exchange liquidity, debt sustainability, economic diversification, institutional quality and policy credibility all influence the risks associated with lending to a sovereign. A new rating institution can provide another analytical perspective, but governments will continue to face pressure to strengthen the underlying economic conditions that determine their capacity to service debt.
The African Peer Review Mechanism, which is hosting the initiative, already has a mandate focused on governance and economic management across African countries. Its current programme identifies the Africa Credit Rating Agency among its continental initiatives, while its 2026 mid-year sovereign credit-rating review examines long-term foreign-currency sovereign ratings across African economies.
For sustainable finance, the implications are broader than sovereign bonds. Public-sector borrowing costs influence the financing environment for state-owned utilities, municipalities and infrastructure agencies, while sovereign yields can also affect the pricing of corporate debt within domestic markets. In countries where governments are major infrastructure investors or provide guarantees for strategic projects, the sovereign risk premium can therefore influence the economics of renewable energy, transport, water and other essential services.
Climate finance makes the issue even more pronounced. African countries face substantial investment needs for adaptation, energy transition and resilient infrastructure, yet many of these investments do not generate immediate financial returns that can easily compensate for high financing costs. A more accurate assessment of country risk could therefore matter for the wider architecture of development finance if it helps investors distinguish between different economies and better understand their fiscal, institutional and structural conditions.
At the same time, the initiative comes as African countries are seeking to deepen domestic capital markets and reduce excessive reliance on external financing. Stronger local bond markets, pension-fund investment, regional financial integration and greater use of development-finance institutions can broaden the sources of capital available to governments and companies. An additional African rating institution could become part of that ecosystem by producing analysis that is relevant to both domestic and international investors.
The challenge will be maintaining analytical independence. For a rating agency to influence the market, its assessments must be trusted even when they are less favourable to the governments or institutions being evaluated. That requires transparent methodologies, reliable data, strong governance arrangements and clear separation between rating decisions and political or commercial interests. These considerations will be closely watched as AfCRA develops its operating model.
The initiative also reflects a wider debate about how risk is measured in emerging markets. African officials have for years argued that international perceptions of the continent can sometimes fail to distinguish adequately between individual economies, leaving countries with very different fiscal positions and economic structures exposed to broad risk assessments. Africanews reported that the AU’s case for AfCRA is partly based on the need for African economies to be assessed using more granular information and greater local knowledge.
For investors, the introduction of another rating institution could provide an additional source of information rather than a replacement for established international agencies. The value of that information will ultimately depend on whether it improves market understanding and reduces information gaps. For African governments, the more immediate issue remains the same: how to secure sufficient financing for development without allowing the cost of that financing to undermine fiscal space.
 That makes the credit-rating debate an important part of Africa’s sustainability conversation. Sustainable development depends not only on the availability of capital but also on its price, maturity and allocation. As African economies invest in energy systems, climate resilience, water infrastructure, transport networks and productive industries, the structure of sovereign risk assessment can have consequences well beyond financial markets. AfCRA’s launch therefore places the cost and quality of capital alongside climate finance, domestic resource mobilisation and infrastructure investment as part of the continent’s broader development-finance challenge.