
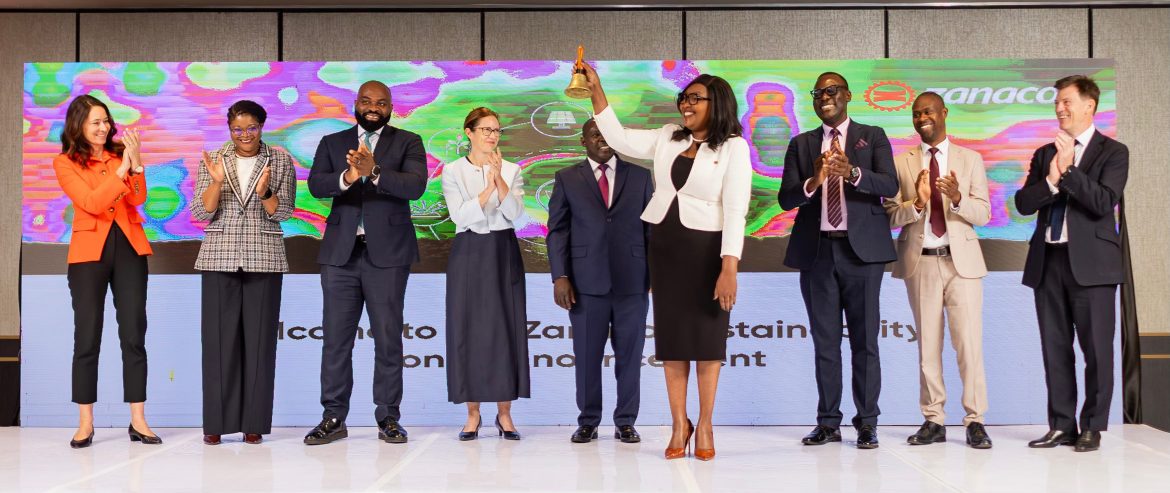
Zambia National Commercial Bank (Zanaco) has launched a US$100 million medium-term note programme aimed at mobilising long-term capital for environmental and social projects, opening a new financing channel for renewable energy, climate-resilient agriculture, energy efficiency, small and medium-sized enterprises, affordable housing, healthcare and education. Announced in Lusaka on September 23, 2026, the programme begins with a planned US$50 million sustainability-bond tranche targeting institutional investors, with British International Investment (BII), the UK’s development finance institution, committing US$15 million to the initial issuance and providing technical support for Zanaco’s Sustainability Bond Framework. The Lusaka Securities Exchange (LuSE) has described the transaction as the first sustainability bond issued by a Zambian bank, giving the deal significance beyond Zanaco as Zambia seeks to deepen its domestic capital markets and broaden the sources of finance available for climate and development priorities.
The programme is structured in two US$50 million tranches. While the first tranche is being positioned as a sustainability bond, Zanaco has said the use of proceeds for the second US$50 million tranche will be disclosed when it is issued. The structure builds on an announcement made in October 2025, when Zanaco and LuSE outlined plans for a US$100 million sustainability-bond programme. At that stage, the proposed structure consisted of a US$50 million private placement followed by a US$50 million public offer. The current programme therefore represents the transition from an announced financing ambition to an active capital-markets instrument.
For the first tranche, the proceeds are expected to be allocated to projects and activities covered by Zanaco’s Sustainability Bond Framework. These include renewable-energy projects, energy efficiency, climate-resilient agriculture, financing for SMEs, affordable housing, healthcare and education. Zanaco says the framework is aligned with the International Capital Market Association’s Sustainability Bond Guidelines, Green Bond Principles and Social Bond Principles, as well as Zambia’s regulatory framework for green finance. The Bank of Zambia lists its Green Loans Guidelines among the regulatory guidelines applicable to the financial sector, while the Securities and Exchange Commission has established requirements governing green bonds, including disclosure, project selection, management of proceeds and external review.
That framework is important because sustainability bonds differ from conventional debt primarily through the way capital is earmarked and subsequently reported. According to ICMA, sustainability bonds are use-of-proceeds instruments in which funds are applied to a combination of eligible green and social projects. The framework calls for transparency around the use of proceeds, project evaluation and selection, management of funds and reporting. For investors operating in emerging markets, these mechanisms can provide greater visibility into how proceeds are allocated and what environmental or social outcomes are being measured.
BII’s US$15 million commitment provides an institutional anchor for the first tranche while also extending an existing financing relationship with Zanaco. BII previously provided the bank with a US$50 million financing facility, including an initial US$30 million tranche, to support lending to micro, small and medium-sized enterprises and climate-related projects. The development finance institution’s involvement in the new transaction also reflects a broader shift in African sustainable finance towards using development capital not only to fund projects directly but also to help financial institutions establish instruments capable of attracting additional private investment.
For Zambia, that mobilisation question is particularly important. The country needs investment across energy, agriculture, infrastructure and social services at a time when fiscal resources remain constrained and climate-related disruptions can affect economic output. Zambia’s reliance on agriculture and hydropower creates a direct connection between climate conditions and economic performance. Drought, for example, can reduce agricultural production and rural incomes while also affecting hydropower generation, electricity availability and the operating costs of businesses. Financing mechanisms that bring institutional capital into climate-resilient agriculture, renewable energy and energy efficiency therefore have implications for productive capacity as well as environmental outcomes.
Agriculture is one of the areas where the bond’s structure could have a direct economic effect. Climate-resilient agricultural financing can include investment in irrigation, water management, climate-smart production systems, storage and technologies that reduce exposure to rainfall variability. The objective is not simply to finance a category labelled as sustainable, but to improve the ability of farmers and agricultural businesses to continue producing and investing under increasingly uncertain climatic conditions. For a country where agricultural performance has significant implications for food security, rural employment and household incomes, the availability and cost of such capital can influence the resilience of the wider economy.
The same logic applies to energy. Renewable generation and energy-efficiency projects can help businesses and households reduce exposure to power shortages and high operating costs while supporting diversification of Zambia’s electricity system. The country has already begun developing a domestic green-bond market through corporate issuance. In 2023, Copperbelt Energy Corporation registered a US$200 million green-bond programme, which was designed to finance renewable-energy generation and potentially energy-storage investments. According to the United Nations Development Programme, CEC Renewables subsequently issued about US$150 million through two green-bond tranches to support two solar plants with a combined capacity of 196 MW. Zanaco’s programme consequently enters a market where green debt has already demonstrated that Zambian capital-market instruments can be linked to physical energy assets.
The difference is that Zanaco’s instrument combines environmental and social uses of proceeds and is being issued by a commercial bank rather than an energy company. That creates a potentially broader connection between the capital market and Zambia’s productive economy. Financing for SMEs, for instance, could reach enterprises that do not have direct access to international capital markets but depend on banks for working capital and investment finance. Zambia’s Ministry of Small and Medium Enterprise Development has described MSMEs as accounting for more than 90% of businesses in the country, underscoring the importance of financial institutions in supporting business formation, employment and expansion.
The transaction also comes as LuSE seeks to expand the pipeline of thematic debt instruments. Nicholas Kabaso, Chief Executive Officer of the Lusaka Securities Exchange, said the exchange intends to work with market participants on additional thematic bond issuances while seeking to simplify issuance procedures and standardise reporting and verification requirements. Such infrastructure matters because the growth of a sustainable-finance market depends not only on individual transactions but also on repeatable processes that reduce the cost and complexity of issuing and monitoring labelled debt.
For institutional investors, the development creates another avenue through which capital can be exposed to Zambia’s banking and sustainable-finance market. But the longer-term credibility of such instruments will depend on the quality of project selection, allocation of proceeds, reporting and verification. ICMA’s principles place considerable emphasis on transparency and disclosure precisely because the credibility of sustainable debt depends on investors being able to understand where capital goes and how issuers report environmental and social outcomes. Zambia’s own regulatory framework similarly requires disclosure and oversight around green bond issuance.
The programme therefore sits at the intersection of three developments in Zambia’s economy: the search for private capital to complement constrained public resources, the growing need to finance climate resilience and the gradual expansion of domestic capital markets. For banks, sustainability bonds can provide an additional funding channel while enabling them to direct lending towards sectors exposed to climate and development pressures. For investors, they provide a structured instrument linked to defined categories of expenditure. For policymakers, the development of a credible thematic debt market can help broaden the financial system’s role in supporting infrastructure and productive investment without relying exclusively on public expenditure or concessional development finance.
The significance for the wider African market is also relevant. Across the continent, governments and financial institutions face a similar financing gap: climate adaptation, renewable energy, resilient agriculture and essential social infrastructure require capital on a scale that public budgets and traditional development assistance cannot provide alone. Domestic financial institutions are therefore increasingly important intermediaries between global pools of capital and African businesses and projects. The Zanaco transaction illustrates how development-finance institutions can participate as anchor investors and technical partners while local banks and capital markets provide the platform through which financing can be deployed domestically.
The immediate test for the programme will be execution: completing the first tranche, allocating the proceeds to eligible projects and maintaining transparent reporting as the financed portfolio develops. The second US$50 million tranche will provide another indication of how the market evolves and which sectors can attract capital under the programme. LuSE’s intention to develop further thematic issuance, combined with Zambia’s existing green-bond experience, suggests that the country’s sustainable-finance market is moving from isolated transactions towards a broader capital-market segment. For Zambia’s businesses, investors and policymakers, the importance of that transition lies less in the label attached to a bond than in whether it succeeds in converting institutional capital into productive investment, stronger infrastructure and greater economic resilience.
In that sense, Zanaco’s US$100 million programme is not simply another debt issuance. It represents an attempt to connect Zambia’s banking sector, institutional investors, development finance and domestic capital markets around projects where environmental resilience and economic performance increasingly overlap. Its longer-term significance will ultimately be measured by the capital mobilised, the projects financed and the transparency with which investors can assess what that capital has achieved.