
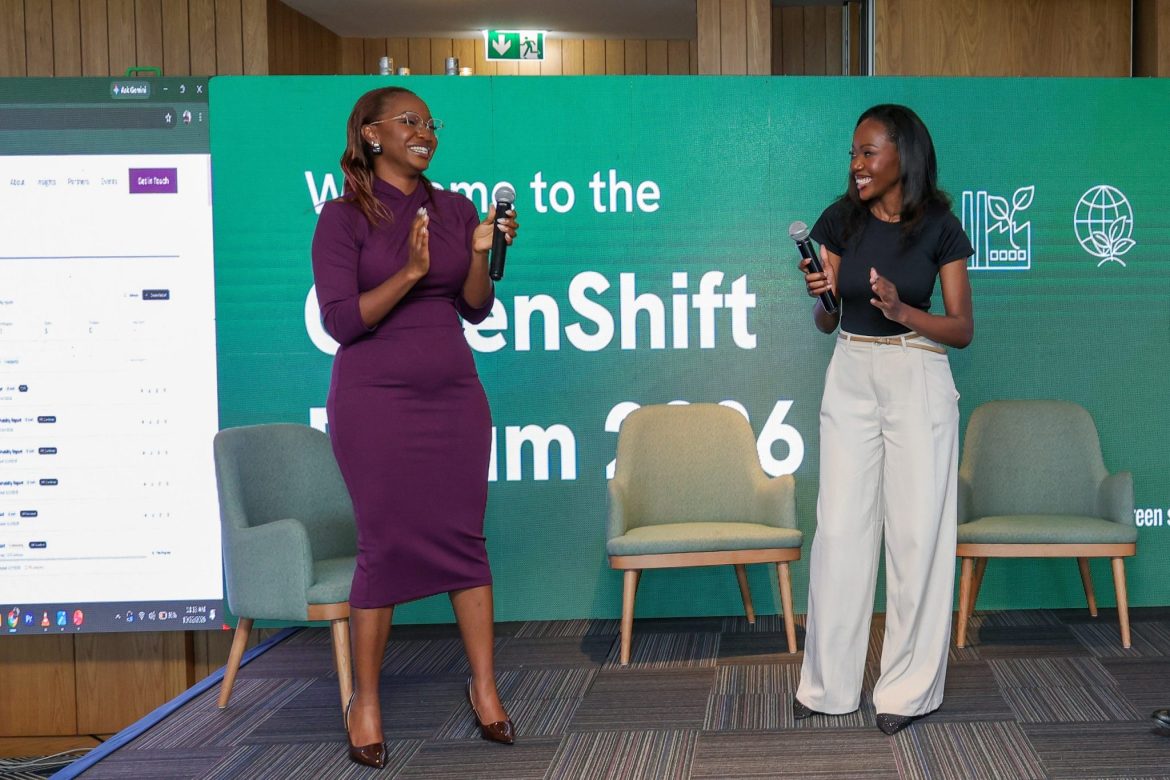
Kenyan businesses face a growing challenge in turning environmental, social and governance (ESG) commitments into reliable disclosures, as sustainability reporting moves closer to regulatory expectations, investor scrutiny and operational decision-making. Discussions at the GreenShift Forum 2026 in Nairobi highlighted the importance of traceable company data, consistent reporting processes and technology in helping organisations demonstrate their sustainability performance.
The forum, held on 22 October 2026, brought together business leaders, sustainability practitioners, financiers and policymakers to examine how companies can translate environmental and social objectives into measurable action. Among the issues raised was the difficulty of gathering information across departments, responding to different reporting frameworks and obtaining credible data from suppliers. These challenges are shaping demand for digital systems such as the Ardena Platform, developed by Ardena Consulting to support ESG data management and reporting.
The debate comes as Kenya prepares for the phased adoption of international sustainability disclosure standards. According to the International Financial Reporting Standards Foundation’s jurisdictional profile for Kenya, the country’s roadmap provides for the mandatory application of IFRS S1 and IFRS S2 to public interest entities for annual reporting periods beginning on or after 1 January 2027. Large entities outside that category are scheduled to follow from 2028, with small and medium-sized entities following from 2029. The roadmap allows earlier adoption.
The requirements are intended to improve the consistency of information about sustainability-related risks and opportunities that could affect an organisation’s prospects. For businesses, however, meeting disclosure expectations will depend on more than publishing a sustainability report. They will need systems capable of collecting, checking and explaining the information behind the figures and statements they release.
ESG information is often spread across departments with different responsibilities and record-keeping practices. Facilities teams may hold electricity and water consumption data, human resources departments manage workforce information, procurement teams maintain supplier records, while risk and compliance functions oversee governance procedures. Where these records use different definitions, reporting periods or measurement methods, consolidating them into a consistent disclosure can become difficult.
A reliable process establishes who is responsible for each metric, where the data originates and how it is verified. It should also retain documentation showing how calculations were made, what assumptions were used and why figures may have changed between reporting periods. Without these controls, errors can be repeated, inconsistencies can go undetected and companies may struggle to substantiate statements when questioned by investors, lenders, customers or regulators.
The quality of ESG information can also influence commercial decisions. Lenders may request evidence of environmental and social performance when assessing projects or monitoring financing conditions, while investors increasingly need comparable information to understand exposure to climate-related risks. Management teams can use the same data to identify inefficiencies, assess progress against targets and determine whether planned investments are delivering the intended results.
Kenyan organisations must also navigate a reporting landscape in which different frameworks serve different purposes. The Global Reporting Initiative Standards focus on reporting an organisation’s impacts on the economy, environment and people, while the IFRS Sustainability Disclosure Standards are designed to provide information relevant to investors’ assessments of sustainability-related risks and opportunities. Industry-specific SASB Standards can help identify financially relevant sustainability topics, while the Task Force on Climate-related Financial Disclosures framework has influenced climate reporting practices and informed the development of newer standards.
These frameworks are not interchangeable. A company may be able to reuse some underlying information, but reporting boundaries, materiality assessments and metric definitions can differ. Businesses therefore need to map data carefully to the requirements that apply to them rather than assuming that one set of figures can be transferred unchanged across every disclosure.
For organisations with limited specialist capacity, this process can create a substantial administrative burden. Staff must identify applicable requirements, collect records, test their accuracy, reconcile inconsistencies and secure internal approvals. Building a reporting process that operates throughout the year can reduce last-minute work and give management a clearer view of information gaps before disclosures are due.
Supplier data presents a further challenge, particularly where a company’s environmental footprint extends beyond its own facilities. Information about purchased materials, transport, outsourced services and other value-chain activities may be held by independent suppliers with different levels of reporting capacity.
Large companies may have dedicated sustainability teams and established digital systems, while smaller suppliers may depend on spreadsheets, invoices or paper records. Detailed information requests can place additional demands on businesses that lack the staff or resources to respond quickly. Clear definitions, proportionate requests and practical guidance can help improve the quality of information without creating unnecessary barriers for smaller suppliers.
The issue is particularly important for greenhouse gas reporting. Indirect emissions can depend on information collected from suppliers, transport providers and other organisations across a value chain. Companies need to document their calculation methods, explain the use of estimates and distinguish verified information from incomplete data. Reporting should not imply a level of precision that the underlying evidence cannot support.
Technology is increasingly being considered as a way to organise these processes. Ardena Consulting, co-founded by Njoki Kamau-Mbugua and Stephanie Ojee, developed the Ardena Platform to support ESG data collection, emissions calculations, dashboards, reporting-framework mapping and audit trails. The company says the platform can map information to frameworks including GRI, SASB, TCFD, IFC Performance Standards and relevant Kenyan disclosure requirements.
Ardena also describes mobile data collection and workflows designed to accommodate information from suppliers operating with limited connectivity or informal record-keeping systems. Such functions could help organisations consolidate information across sites and departments, although their effectiveness will depend on implementation, data quality and how consistently users follow the underlying processes.
Digital tools cannot, on their own, guarantee accurate sustainability reporting. Software can flag missing values, apply validation rules and maintain records of changes, but it cannot independently establish whether a company has selected the appropriate reporting boundary, whether a supplier’s figures are credible or whether the information reflects actual operating conditions. Those judgments require competent staff, documented procedures and management oversight.
The distinction matters as sustainability reporting becomes more closely connected to business planning. An organisation tracking electricity consumption, for example, needs more than an annual total to understand whether energy-efficiency investments are working. It may also need to consider changes in production volumes, operating hours, weather conditions and the proportion of electricity obtained from different sources.
Similar questions apply to waste, water use, workplace safety and social programmes. Companies need to distinguish between resources invested, activities completed and outcomes achieved. A policy, training session or new monitoring system may represent progress in implementation, but evidence of changes in practice or performance is needed to establish whether the intervention has achieved its intended purpose.
For boards and senior management, this means treating ESG information as part of the organisation’s internal control and decision-making systems rather than a report assembled at the end of the financial year. Clear ownership of metrics, regular data reviews and documented approval processes can help identify problems earlier and connect sustainability targets with operational responsibilities.
Kenya’s phased adoption of IFRS S1 and IFRS S2 gives businesses a defined timetable to strengthen their reporting capacity. Companies that begin by reviewing their existing data, identifying gaps and assigning responsibility for key indicators will be better positioned to prepare for applicable requirements. The readiness process will also require attention to staff training, supplier engagement and the reliability of the systems used to produce disclosures.
Ultimately, the credibility of ESG reporting will depend on whether the information can be traced, explained and used to assess performance. Digital platforms can make that process more manageable, but the central responsibility remains with the organisations publishing the information. As reporting expectations develop, the test for Kenyan businesses will be whether sustainability data can support both credible disclosure and better decisions about how they operate.