
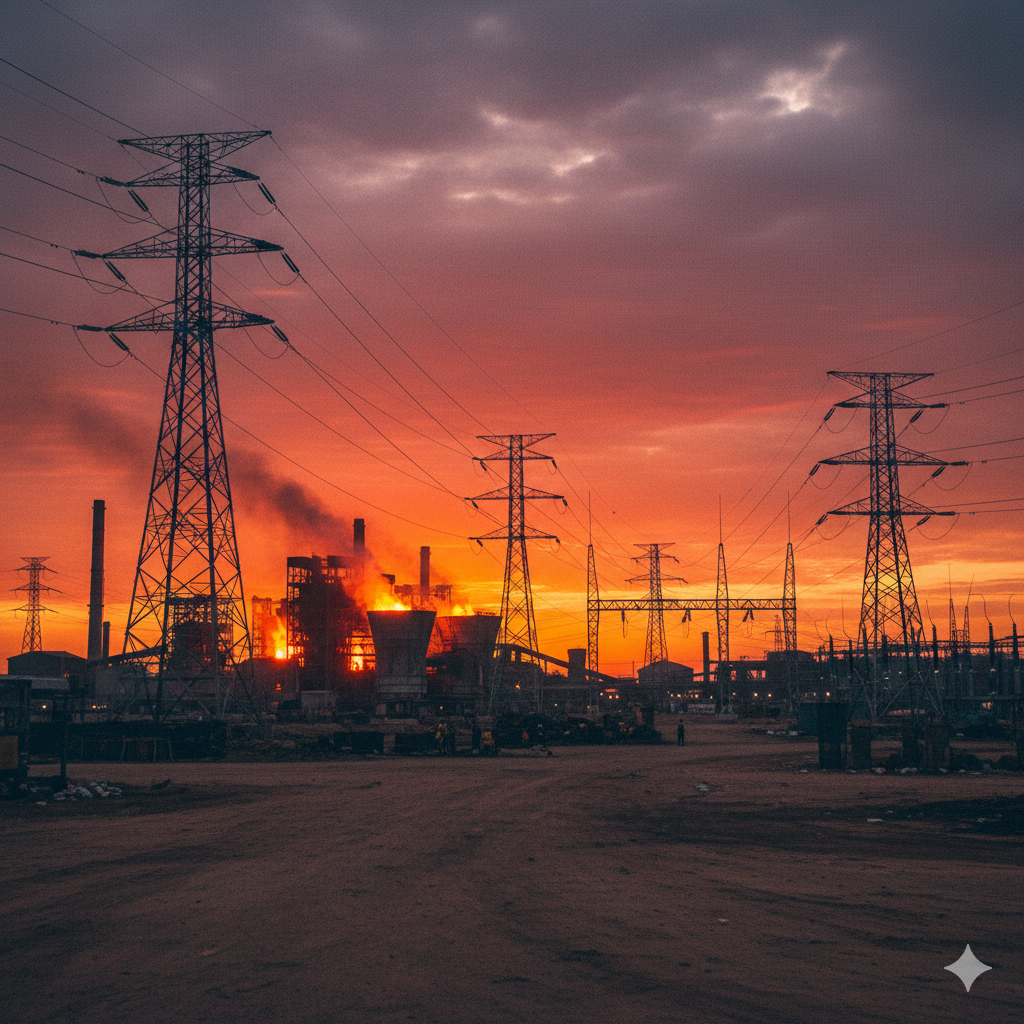
Africa’s decarbonisation agenda is increasingly moving beyond national climate targets and into the economics of industrial production, as manufacturers face pressure to lower emissions while controlling energy costs, protecting export markets and attracting investment. Across the continent, governments and industry are beginning to treat energy efficiency, cleaner production, low-carbon technologies and circularity as tools for maintaining competitiveness in global markets, a shift that could reshape investment decisions across sectors from cement and steel to manufacturing, agriculture and logistics.
The change reflects a broader reality for African economies. Decarbonisation is no longer confined to environmental regulation or international climate negotiations. It is increasingly influencing the conditions under which companies access markets, finance and global value chains. As major trading partners introduce carbon-related requirements and investors place greater emphasis on transition risks, the emissions profile of African production could become a factor in determining where goods are manufactured, how they are financed and whether they remain competitive internationally.
 For countries with large industrial bases, the pressure is already becoming tangible. South Africa, the continent’s most industrialised economy, is developing industrial decarbonisation strategies around sectors that are central to exports and domestic employment. The country’s National Cleaner Production Centre has identified decarbonisation, digitalisation and diversification as components of a broader industrial competitiveness strategy, with energy and resource efficiency among the immediate measures available to manufacturers. Industry programmes supported by the centre have reportedly delivered more than 9.5 million tonnes of greenhouse-gas mitigation over the past 15 years.
The issue is particularly important for South African steel, chemicals, cement and other energy-intensive industries exposed to international markets. The European Union’s Carbon Border Adjustment Mechanism is increasing the importance of emissions measurement and lower-carbon production for exporters supplying the European market. South Africa is the continent’s second-largest steel producer, and its steel industry supports automotive manufacturing, construction, mining and thousands of jobs. Its exposure to European markets means that the cost and carbon intensity of production increasingly intersect with questions of trade competitiveness.
For African manufacturers, the challenge is complicated by structural constraints that are largely outside the control of individual companies. Electricity reliability remains uneven across many markets, the cost of capital is high and industrial infrastructure is often ageing. Investments in electrification or renewable energy can therefore deliver environmental benefits while also addressing operational risks, but only where the underlying power systems and financing conditions allow those investments to scale.
According to recent industry analysis, Africa’s industrial decarbonisation challenge is increasingly a competitiveness question because energy costs, power reliability, productivity and exposure to carbon-linked trade measures are becoming interconnected. Energy efficiency is particularly significant because reducing the amount of energy required to produce a unit of output can lower both operating costs and emissions.
This creates a different policy calculation for governments. Rather than treating decarbonisation as an additional compliance cost, industrial policy can increasingly link cleaner production with productivity, export development and investment attraction. The distinction matters for African economies where manufacturing remains relatively small compared with the size of the working-age population and where governments are seeking to move beyond commodity exports into higher-value production.
The cement industry illustrates the scale of the opportunity and the risk. Africa is entering a period of rapid urbanisation and infrastructure development, while much of the continent’s future building stock has yet to be constructed. A regional dialogue convened by the United Nations Industrial Development Organization in Ethiopia in July brought together more than 110 participants from 39 countries, including 23 African countries, to examine how the continent can expand cement production without locking in high-emission infrastructure. The discussions focused on technologies and practices including lower-clinker cement, alternative fuels, material efficiency, stronger measurement systems and green public procurement.
The choices made in sectors such as cement therefore carry consequences beyond corporate emissions reports. New factories, power systems, transport corridors and buildings can operate for decades. If they are built around inefficient technologies or carbon-intensive energy sources, future industries may face higher costs to retrofit them or comply with increasingly stringent market requirements. Conversely, investment in efficient equipment, cleaner power and local technology capabilities could reduce operating costs while creating domestic markets for engineering, maintenance and clean-technology services.
Regional integration will also influence how this transition unfolds. In September, COMESA industry ministers highlighted market fragmentation, limited manufacturing capacity, dependence on primary commodities and weak regional value chains as constraints on industrial development. The bloc also committed to regional value chains and an inclusive transition towards a circular economy, while supporting programmes focused on cleaner production, competitiveness, standards and market access.
That regional dimension is important because many African economies are too small individually to build competitive low-carbon industrial ecosystems at scale. Shared standards, regional power markets, cross-border infrastructure and integrated supply chains could allow companies to serve larger markets while spreading the cost of new technologies and production capabilities. The African Continental Free Trade Area could provide an additional market base for industries investing in cleaner production, provided that infrastructure and regulatory barriers continue to fall.
Finance remains the central constraint. Industrial decarbonisation frequently requires large upfront investments in equipment, renewable power, electrification, alternative fuels, digital monitoring and process redesign, while many African companies already face elevated borrowing costs. International climate finance can help reduce some of those barriers, but its effectiveness will depend on whether funding reaches commercially viable industrial projects rather than remaining concentrated in planning, technical assistance and early-stage studies.
The OECD’s 2026 review of financial and technical assistance for industrial decarbonisation in emerging and developing economies illustrates the direction of international financing. Its Industry Decarbonization Program, backed by $1 billion in Climate Investment Funds resources, is structured around national investment plans that combine concessional finance with multilateral development bank and private capital. The programme includes South Africa, Egypt and Namibia among participating countries and covers measures such as energy efficiency, electrification, low-carbon fuels and circular solutions.
For Africa, the effectiveness of such financing will ultimately depend on whether it strengthens productive capacity rather than simply lowering the emissions intensity of existing production. Investments that create local supply chains for clean technologies, build technical skills, improve industrial infrastructure and support African engineering and manufacturing capabilities could have broader economic effects than projects focused only on emissions reductions.
The transition also creates a strategic question for governments about the role of public procurement. State-funded infrastructure represents a major source of demand for cement, steel, transport equipment and other industrial products. Incorporating credible environmental performance standards into procurement could create markets for lower-carbon materials while giving domestic producers an incentive to invest in cleaner production. But standards that are introduced without financing or technical support could also raise costs for smaller manufacturers and deepen the gap between large formal producers and smaller enterprises.
This balance will become increasingly important as African governments attempt to reconcile climate commitments with employment, industrialisation and fiscal constraints. At the Fourteenth Conference on Climate Change and Development in Africa, held in Addis Ababa in September, policymakers and institutions called for a shift from climate pledges towards implementation and greater African agency in financing the transition.
The emerging industrial approach suggests that Africa’s decarbonisation pathway will be judged not only by tonnes of emissions avoided, but by the economic systems built alongside those reductions. For countries seeking to expand manufacturing, develop regional value chains and reduce dependence on raw commodity exports, the ability to produce competitively in a lower-carbon global economy is becoming part of the industrialisation challenge itself.
 The immediate task is therefore less about choosing between climate action and economic development than determining whether the two can be built into the same investment decisions. For African industry, cleaner energy, efficient equipment, resilient infrastructure and credible emissions data are increasingly becoming inputs into market access and productivity. The countries and companies that can manage that transition while developing domestic capabilities may be better positioned to retain industrial value as global markets place greater weight on the carbon content of what they buy.