
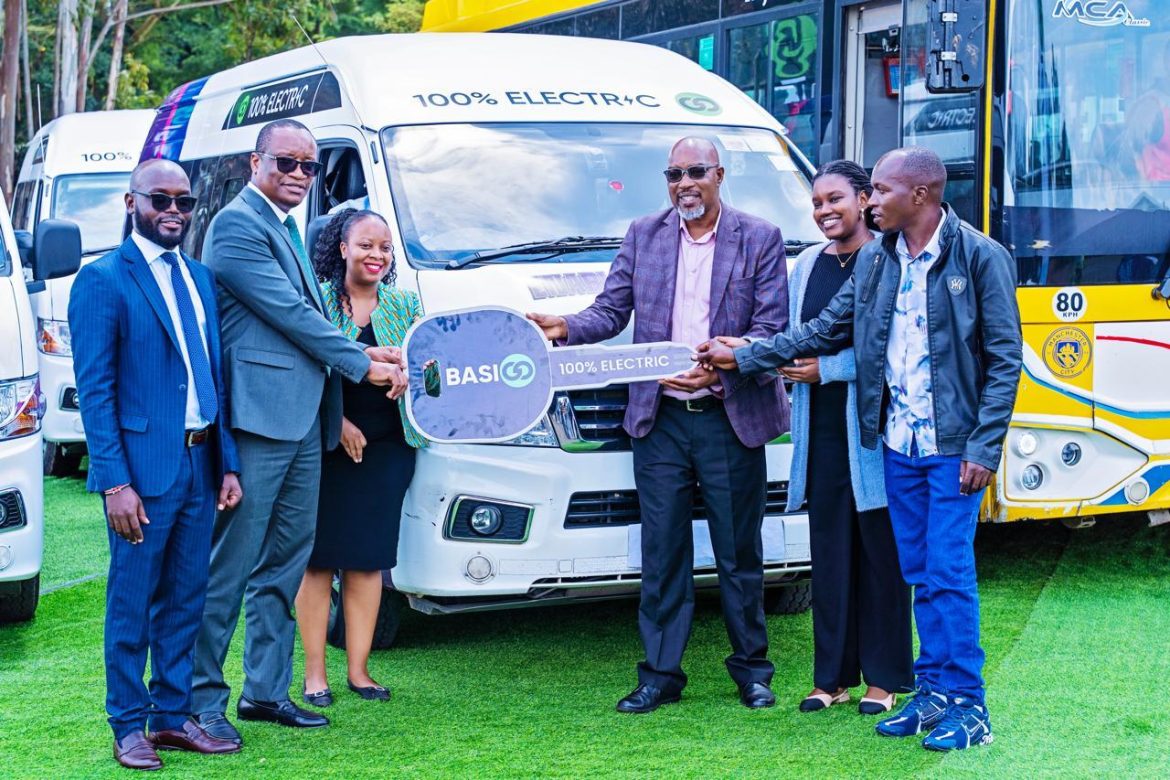
Co-operative Bank of Kenya has committed KSh1.5 billion over 12 months to finance electric public service vehicles, expanding the role of commercial banks in Kenya’s transition towards electric public transport. Announced on 13 November 2026, the programme will target matatu Savings and Credit Co-operative Organisations (Saccos), offering financing for vehicle purchases, charging infrastructure and digital fare collection.
The bank will finance up to 90 per cent of vehicle purchase costs, with operators required to provide the remaining 10 per cent. The programme is structured around Sacco fleet acquisition, allowing transport organisations to seek financing for multiple electric vehicles rather than relying exclusively on individual purchases.
The initiative adds another major lender to Kenya’s emerging electric mobility market, where banks are developing financing products to support the acquisition of electric vehicles and associated infrastructure. NCBA, KCB and SBM Bank have also introduced facilities or partnerships targeting different segments of the market, reflecting growing competition to finance the transition in the transport sector.
Co-operative Bank’s programme builds on its existing relationships with transport Saccos, which organise vehicle ownership and operations across public transport routes. Vincent Marangu, the bank’s Director of Co-operatives Banking, said the fleet-based model was designed around the way Saccos manage vehicles and their operations.
Two 16-seater electric vans supplied by BasiGo have already been delivered to Enabled Mashariki Sacco. Other suppliers participating in the programme include QuantumDrive, MojaEV Africa and Rideence Africa. The involvement of multiple suppliers could widen the range of vehicle options available to operators, although the programme’s eventual scale will depend on vehicle availability, financing terms and the commercial performance of electric fleets.
The bank’s KSh1.5 billion commitment comes as other financial institutions establish dedicated products for electric mobility. NCBA has a KSh2 billion e-mobility financing facility and announced a partnership with BasiGo in August 2026, targeting the deployment of 1,000 electric vehicles. The earlier announcement reported that more than KSh800 million had been deployed through the facility.
Under the NCBA arrangement, established Saccos and companies can access financing of up to 90 per cent over five years, while individual Sacco members qualify for up to 80 per cent financing over four years. The partnership also incorporates BasiGo’s Pay-As-You-Drive model, which allows operators to access electric vehicles through a usage-based payment structure rather than relying solely on conventional asset financing.
Read also:Kenya’s electric mobility financing expands as NCBA and BasiGo target 1,000 electric vehicles
SBM Bank has committed KSh1 billion to green financing for electric and hybrid vehicles over 12 months. Its programme, announced in July, covers both consumers and businesses and includes a partnership with CFAO Mobility Kenya. KCB has also developed financing arrangements for public transport operators through its collaboration with the Matatu Owners Association and ePureMotion.
These facilities do not represent identical investments in electric public transport. SBM’s programme includes hybrid vehicles and private customers, while NCBA’s partnership with BasiGo focuses on commercial electric vehicle deployment. Co-operative Bank’s Sacco-centred approach, meanwhile, places fleet acquisition and supporting infrastructure at the centre of its financing model. Together, the initiatives indicate that electric mobility is becoming a more established area of activity for Kenya’s banking sector.
For transport operators, access to finance remains a central consideration in the transition from conventional vehicles to electric fleets. Electric matatus require an upfront capital commitment, while their commercial viability depends on passenger demand, route distances, daily utilisation, charging access and maintenance costs. Financing structures therefore influence not only whether operators can acquire vehicles, but also how the costs are distributed over the operating life of a fleet.
Sacco-based lending offers one route to managing these requirements. Saccos already coordinate vehicle ownership, route operations and member activities, giving lenders an established institutional structure through which to assess and finance fleet purchases. However, the bank has not disclosed the repayment periods or detailed lending conditions attached to its new programme, leaving the cost of borrowing and the distribution of financial risk to be clarified.
The financing of charging infrastructure is another important part of Co-operative Bank’s approach. Vehicle acquisition alone cannot support a reliable electric public transport network without charging facilities that match route schedules, vehicle capacity and daily operating requirements. Charging access is particularly important for commercial fleets, where extended vehicle downtime can affect passenger services and operator revenues.
Infrastructure providers have begun expanding charging networks beyond Nairobi. In July 2026, BasiGo and Rubis Energy Kenya established a 100-kilowatt direct-current fast-charging station at Sabaki, Athi River. The facility supports CCS2 and GB/T charging standards and is designed to serve electric buses, vans, trucks and compatible passenger vehicles. BasiGo reported an indicative charging price of KSh48 per kilowatt-hour.
Further charging installations have been planned for Meru, Nanyuki and Nyeri, while BasiGo has also reported infrastructure development around terminals and depots in Nakuru, Nyeri, Meru and Nanyuki. These projects require investment in electricity connections, transformers and distribution equipment capable of supporting commercial vehicle charging.
Kenya Power’s reported e-mobility revenue provides another indication of the emerging electricity market. The utility recorded cumulative electric vehicle charging revenue of KSh382 million over the 34 months to April 2026, with monthly charging revenue reaching KSh35 million in February. Its figures also showed that monthly electricity sales to the e-mobility sector had increased more than 113-fold between July 2023 and April 2026.
Electricity pricing will remain a consideration for operators and charging infrastructure providers. In September 2026, the Energy and Petroleum Regulatory Authority revised its e-mobility electricity tariff framework, replacing the previous fixed monthly consumption ceiling with an Energy Consumption Threshold mechanism. The revised framework includes an energy charge of KSh16 per kilowatt-hour for customers supplied at 240 or 415 volts, with applicable off-peak electricity charged at KSh8 per kilowatt-hour.
For electric public transport operators, the relationship between electricity costs, vehicle utilisation and fare revenue will influence the financial performance of fleets. Charging infrastructure must also be located and scaled to support the routes on which vehicles operate. Co-operative Bank’s decision to include charging facilities in its financing programme reflects the need to address these requirements alongside vehicle purchases.
The development of local vehicle supply is creating another part of the market. In February 2026, Rideence Africa and Associated Vehicle Assemblers announced a KSh320 million partnership to begin assembling electric vehicles in Mombasa. The arrangement included plans for 20 Joylong electric high-roof matatus and 132 electric taxis, alongside efforts to expand charging infrastructure.
Local assembly could create opportunities to widen vehicle supply and support the development of maintenance and servicing capacity. However, vehicle prices, production volumes, component sourcing and the availability of spare parts will continue to affect the cost of fleet acquisition and operation.
Co-operative Bank’s KSh1.5 billion commitment adds another source of financing to this developing ecosystem. By combining Sacco-based vehicle lending with support for charging infrastructure and digital fare collection, the programme extends beyond the purchase of electric vehicles to the systems required to operate them commercially.
Its impact will ultimately depend on how quickly the financing is deployed, the number of vehicles acquired and the ability of operators to sustain viable fleet operations. As lenders, vehicle suppliers and energy providers expand their involvement, Kenya’s electric public transport market is increasingly being shaped by the availability of finance and the commercial infrastructure needed to make electric mobility work at scale.