
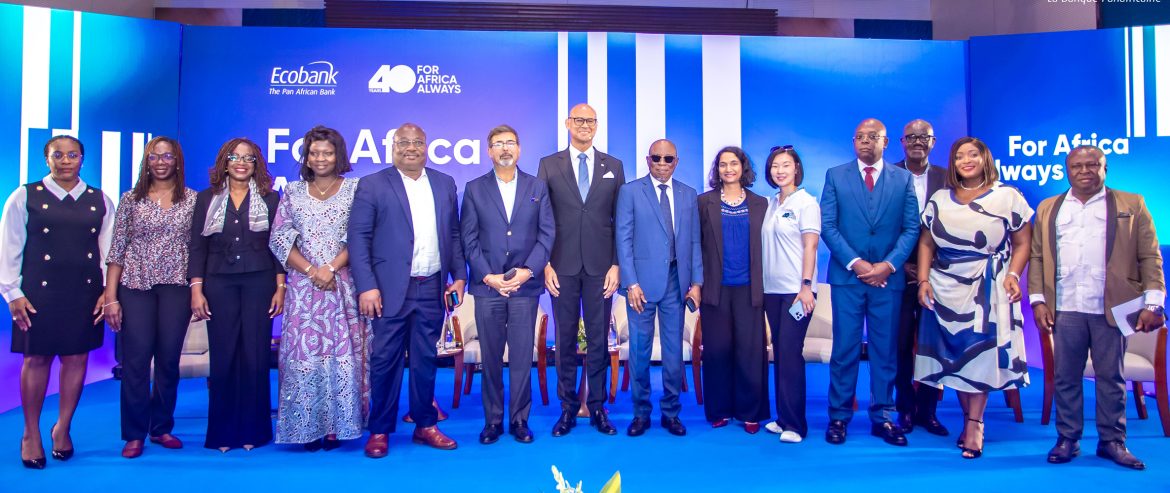
Ecobank Group has committed to directing $2.6 billion in lending towards women-owned businesses and agricultural value chains across Africa by 2030, setting out one of the continent’s larger private-sector financing targets focused on gender inclusion, food systems and regional trade. The commitment, announced on September 24 at the bank’s 40th-anniversary media conference in Lomé, comprises a planned $2 billion loan portfolio for women entrepreneurs through its Ellevate programme and a further $600 million for agriculture-focused small and medium-sized enterprises. Ecobank said the strategy will be implemented across its 34 African markets and is intended to strengthen access to capital, support agricultural value chains and expand participation in cross-border commerce.
The announcement comes as African businesses continue to face structural constraints in accessing long-term finance, while governments and development institutions are seeking greater private-sector participation in agriculture, manufacturing and regional trade. For women entrepreneurs in particular, access to capital remains a persistent constraint. The World Bank noted in March 2026 that women in developing economies continue to experience a financial access gap relative to men, with lack of finance limiting their ability to invest, insure against shocks and expand businesses.
Ecobank’s plan is therefore positioned around two interconnected challenges: the financing constraints affecting women-led enterprises and the capital requirements of Africa’s agricultural transformation. Under Ellevate, the bank intends to build an outstanding loan portfolio of $2 billion dedicated to women entrepreneurs by 2030. Ecobank said the programme has already supported more than 110,000 women-led enterprises and aims to increase its registered client base to 400,000 formal businesses, while creating financing pathways for up to one million female micro-entrepreneurs through expanded digital onboarding and financial inclusion initiatives.
The structure of the proposed financing is also significant. Ecobank said Ellevate will use unsecured and partially secured credit facilities, supported by development-finance-institution guarantee partnerships. The approach is designed to address one of the persistent barriers faced by smaller enterprises: the inability to provide conventional collateral at the scale required by commercial lenders. In practice, the availability of guarantees can allow banks to assume more manageable levels of risk while extending financing to businesses whose assets, cash flows or operating histories may not fit traditional lending models.
The African Development Bank has documented the potential of such risk-sharing mechanisms through its partnership with Ecobank under the Affirmative Finance Action for Women in Africa programme. According to the AfDB, AFAWA’s Guarantee for Growth mechanism can cover up to 75% of the risk on loans to women-led businesses. The partnership helped Ecobank increase its portfolio of women-led businesses from 9,400 in 2021 to more than 83,000 by the end of 2024, with lending reaching $265 million during that period.
Ecobank’s new target represents a substantial expansion of that financing model. The challenge will be converting a headline lending commitment into a sufficiently large pipeline of bankable businesses while maintaining credit quality and ensuring that financing reaches enterprises outside major commercial centres. This is particularly relevant in markets where women-owned businesses are concentrated in informal or micro-scale activities and may lack the financial records, registration documents and collateral typically required by conventional banks.
The second component of Ecobank’s strategy is a $600 million lending commitment to agricultural SMEs and value chains by 2030. Rather than focusing only on seasonal agricultural production, the bank said the financing will cover the broader “farm-to-fork” system, including farmers, aggregators, processors, logistics providers, traders and exporters. This approach reflects the capital requirements of modern food systems, where agricultural productivity depends not only on what happens on farms but also on storage, transportation, processing, market access and trade finance.
That emphasis is increasingly relevant as African countries attempt to reduce food-import dependence while strengthening domestic and regional food markets. The African Development Bank has identified agriculture and food systems as central to Africa’s resilience and economic transformation, while warning that climate shocks, conflict and weaknesses in infrastructure, technology and agricultural logistics continue to constrain progress. The Bank’s Feed Africa strategy specifically emphasises climate-smart agricultural value chains, stronger input and output markets, agro-processing and regional trade opportunities created by the African Continental Free Trade Area.
Ecobank said the agricultural programme will place particular emphasis on climate-smart agriculture, digital payment systems across rural supply chains and structured trade finance. The climate component is relevant because agricultural finance is increasingly exposed to drought, floods, changing rainfall patterns and other climate-related disruptions. Financing production without addressing those risks can leave farmers and agricultural businesses vulnerable to repeated losses and weaken lenders’ portfolios.
Recent African development programmes illustrate why financing needs to extend beyond seasonal inputs. In Zimbabwe, an African Development Bank-supported agricultural programme that concluded in 2026 combined improved inputs and farming technologies with climate-smart practices, reaching more than 188,000 farming households. The programme also used a seed revolving fund that provided financing to more than 90,000 farmers and recorded a repayment rate above 90%.
Elsewhere, the AfDB’s 2026 agricultural portfolio has increasingly focused on strengthening complete value chains. Its $200 million financing for Nigeria’s second phase of the National Agricultural Growth Scheme, for example, includes improved inputs, value-chain development, digital and climate-smart agriculture and agricultural data systems. Such programmes demonstrate the growing emphasis among development institutions on treating agricultural finance as part of a wider production and market system rather than as a stand-alone farm loan.
For Ecobank, the regional dimension is central to both commitments. The bank said its Single Market Trade Hub connects more than 60,000 businesses and is intended to help African companies identify trading partners and participate in cross-border commerce under the AfCFTA. The platform provides businesses with access to information about markets, importers, exporters and trade requirements, alongside Ecobank’s broader payment and financial infrastructure.
This matters because access to finance does not automatically translate into access to markets. A woman-owned agribusiness may be able to secure working capital but still face difficulties finding buyers, receiving cross-border payments, meeting export requirements or managing currency exposure. Similarly, an agricultural processor may have sufficient demand but lack the trade finance needed to purchase raw materials or fulfil a larger regional order. Linking lending with digital payments and market-access infrastructure can therefore address several constraints simultaneously.
The AfCFTA provides the policy context for that strategy. The agreement aims to reduce barriers to intra-African trade and investment and create a continental market for goods and services. Ecobank’s strategy effectively positions its financial network as an infrastructure layer through which some of that regional commerce can take place. The extent to which this translates into increased intra-African trade will depend on factors beyond banking, including customs procedures, transport infrastructure, standards, border processes and the competitiveness of African producers.
Read also:Ecobank and AGRA Sign Major Agriculture Finance Deal to Boost African Farmers and Agribusinesses
The financing commitment also highlights the increasingly important relationship between commercial banking and development finance. Ecobank said it plans to use DFI guarantee partnerships and risk-sharing facilities to expand lending. The model reflects a broader shift in development finance towards mobilising commercial capital rather than relying exclusively on direct public or concessional lending.
For Africa’s financial markets, that distinction matters. Development institutions have limited balance sheets relative to the scale of the continent’s financing needs. Commercial banks, institutional investors and private capital therefore have a role to play in expanding the pool of available finance. The effectiveness of risk-sharing instruments can depend on whether they reduce perceived risk sufficiently to encourage commercial lenders to enter markets and customer segments they might otherwise avoid.
The gender component is particularly relevant because women entrepreneurs are often concentrated in smaller enterprises and sectors where financing needs are modest individually but significant in aggregate. The World Bank has highlighted that women-owned businesses can face difficulties establishing formal financial histories and meeting conventional lending requirements. In Somalia, for example, the Bank reported in 2026 that more than half of household businesses were owned by women, while more than half of those businesses were unable to meet their credit needs without stronger financial, business-registration and digital systems.
The challenge for Ecobank will therefore extend beyond disbursing $2 billion. The scale of the commitment will require systems capable of identifying viable enterprises, assessing risk where conventional credit histories are limited, providing suitable loan products and monitoring whether financing produces sustainable business growth. For agricultural borrowers, the same challenge applies alongside additional exposure to weather, commodity prices and market disruptions.
Ecobank’s announcement also comes as Africa’s agricultural policy agenda is increasingly shifting from food production towards food-system transformation. The African Development Bank’s recent work emphasises the importance of private investment, climate-smart technologies, agro-processing and stronger regional value chains. At the Africa Food Systems Forum in September 2026, the Bank and African ministers discussed the need to move from emergency agricultural interventions towards more market-driven and resilient food systems.
That transition requires capital at several points in the chain. Farmers need inputs and equipment; aggregators require working capital; processors need machinery; logistics companies need vehicles and storage infrastructure; exporters need trade finance; and digital platforms require investment to connect participants. A financing programme that reaches across these segments can potentially address bottlenecks that a farm-level lending programme alone would leave unresolved.
Ecobank’s $2.6 billion commitment should therefore be viewed within the wider contest for capital to support Africa’s economic transformation. The bank is not committing $2.6 billion as a single upfront investment. Rather, the figure represents targeted outstanding loan portfolios to be built by 2030, meaning actual deployment will occur through lending activities over time and will depend on eligible demand, credit assessment, risk-sharing arrangements and market conditions. Ecobank’s own announcement describes the targets as lending commitments rather than a single disbursement.
The broader significance will ultimately depend on what the financing produces. For women-led businesses, the relevant outcomes will include whether more enterprises formalise, invest, create jobs and enter larger supply chains. For agriculture, the measure will extend beyond the amount lent to whether financing helps businesses increase productivity, withstand climate shocks, process more agricultural output locally and participate in regional markets.
Ecobank’s 40th-anniversary announcement consequently places commercial finance at the centre of two of Africa’s longer-term development challenges: expanding productive opportunities for women and building agricultural value chains capable of supplying growing domestic and regional markets. The next phase will be measured less by the size of the announced target than by how effectively capital reaches businesses that have historically struggled to access it, and whether those businesses can convert finance into durable productive capacity across Africa’s increasingly integrated economy.