
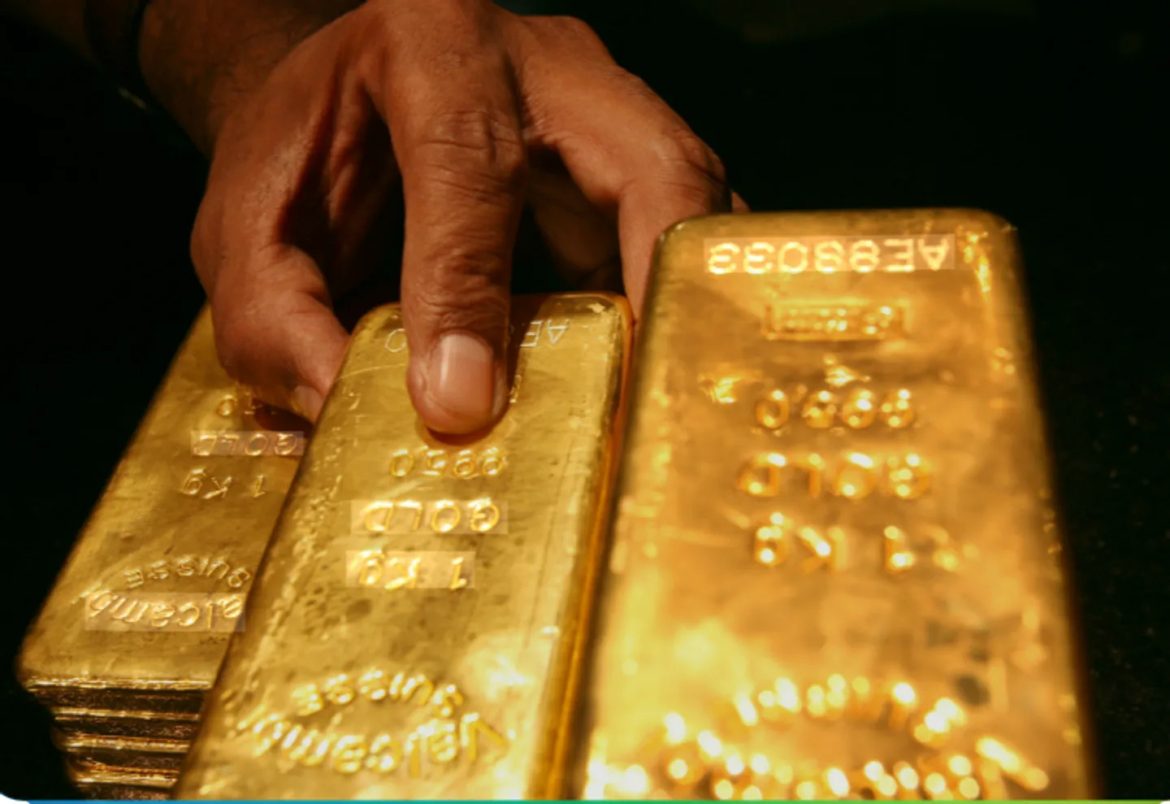
Gold’s retreat below $3,800 an ounce on November 18 is beginning to expose fiscal and foreign-exchange risks across some of Africa’s largest producing economies, as governments from Ghana and Mali to Burkina Faso, Guinea, Tanzania, South Africa and Sudan confront weaker export receipts after a record-breaking rally earlier in 2026.
The metal traded at about $3,792 an ounce, its lowest level in a year and more than a quarter below the peak reached in late February, according to TRT Afrika. Although the price remains high by historical standards, the speed of the decline matters for countries that rely on gold to generate foreign currency, collect mining royalties and support public spending.
Gold is the largest export in Mali and Burkina Faso, while Ghana now earns more from the metal than from cocoa. The consequences of a prolonged price decline would therefore extend beyond mining companies. Lower export proceeds can reduce the supply of dollars in domestic markets, weaken national currencies and increase the local-currency cost of servicing foreign debt, importing fuel and purchasing machinery.
For finance ministries, the immediate exposure is through mining royalties, corporate taxes, dividends from state holdings and export-related charges. Government revenue forecasts are often prepared using assumptions about commodity prices and production volumes. When market prices fall sharply, the gap between projected and actual receipts can force spending adjustments, increase borrowing requirements or delay infrastructure programmes.
The extent of the impact will vary by country. Ghana, Africa’s largest gold producer, has a diversified mining industry and substantial production from both large companies and small-scale operators. Gold nevertheless plays an important role in the country’s balance of payments and foreign-exchange position. A weaker price could narrow the revenue gains that helped cushion Ghana against pressure on the cedi and the rising cost of imported goods.
In Mali and Burkina Faso, where gold accounts for a larger proportion of exports, the fiscal exposure is more concentrated. Both governments depend on mining revenue while also facing heavy security, humanitarian and development spending. Reduced receipts would leave less room for investment in roads, electricity, water systems, schools and public health without additional borrowing or cuts elsewhere.
The decline also tests efforts by African governments to capture more value from mineral production. Burkina Faso opened a gold refinery in September, followed by Guinea a month later, as both countries sought to reduce raw mineral exports and retain a greater share of processing income at home.
Domestic refining can create industrial activity, improve oversight of mineral flows and reduce dependence on overseas processing. It does not, however, insulate producers from international prices. Refinery economics still depend on adequate throughput, reliable electricity, competitive operating costs and access to certified markets. A sustained decline could reduce margins across the production chain, particularly for facilities operating below capacity.
The pressure is likely to be most acute at high-cost mines. Gold remains well above the roughly $1,800 to $2,000 range recorded three years ago, meaning many established operations should remain profitable. But mines with declining ore quality, high energy costs, ageing equipment or significant security expenses have less room to absorb lower prices.
Companies may respond by reducing exploration, postponing capital expenditure or concentrating production on higher-grade deposits. Such decisions can affect contractors, transport operators and communities whose incomes depend on mining activity. In regions where mines are among the few large formal employers, even a limited reduction in investment can weaken local businesses and municipal revenue.
The downturn follows an exceptional rise in early 2026. Gold reached about $5,600 an ounce on January 29 and averaged approximately $5,020 in February as central-bank purchases, geopolitical uncertainty and expectations of looser monetary policy pushed investors towards safe-haven assets.
That environment subsequently changed. Higher oil prices added to inflation concerns, while expectations of tighter monetary policy strengthened the dollar and increased the appeal of interest-bearing assets. Gold does not generate interest, making it less attractive when US bond yields rise and investors can earn stronger returns from dollar-denominated securities.
Those global monetary shifts have direct consequences for Africa. Many governments borrow in dollars while collecting most domestic revenue in local currency. If lower gold receipts coincide with a stronger dollar, producing countries can face pressure on both sides of their public accounts: weaker export income and higher debt-service costs.
The adjustment is not entirely negative. Some African central banks hold gold as part of their reserves or are increasing domestic purchases to diversify away from foreign currencies. Lower prices could reduce acquisition costs, although central banks must balance that opportunity against the loss of export income and the liquidity requirements of managing external payments.
The decline could also sharpen scrutiny of how mining windfalls are managed. Commodity booms can produce rapid increases in public revenue, but those gains are vulnerable when budgets become dependent on prices that cannot be sustained. Stabilization funds, conservative price assumptions and transparent royalty management can help governments spread mineral income across economic cycles rather than expand permanent spending during temporary rallies.
For producing countries, the central issue is therefore not whether gold remains valuable, but whether public finances and mining strategies can withstand volatility. The metal continues to benefit from central-bank demand, jewellery purchases and industrial uses in electronics, medicine, dentistry and aerospace. Those sources of demand may support the market, but they do not remove the risk of further price movements.
At about $3,800 an ounce, gold remains historically expensive and most major mines are likely to continue operating. What has ended, at least for now, is the exceptional price environment that delivered unusually strong revenue to producers during the first months of 2026.
For African governments, the adjustment strengthens the economic case for processing minerals locally, improving mining-sector governance and diversifying exports. It also demonstrates the limits of relying on commodity prices to stabilize currencies or finance long-term development. If gold remains below $4,000, the effects are likely to appear gradually through lower tax receipts, reduced foreign-exchange inflows, delayed investment and greater pressure on mines operating at the edge of profitability.
The strongest protection will not come from anticipating the next movement in the gold market. It will depend on whether producing countries can convert periods of high prices into resilient public finances, competitive domestic industries and infrastructure capable of supporting economic activity after the commodity cycle turns.