
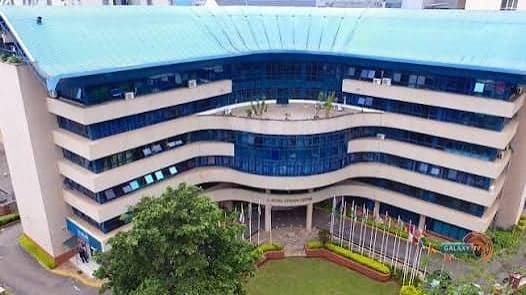
Shelter Afrique Development Bank has launched its first sustainability bond denominated in West African CFA francs, targeting investment in affordable and sustainable housing across West Africa as the regional development lender seeks to use capital markets to address housing needs. Announced on 9 October, the issuance marks a new step in the bank’s financing strategy, although the scale of funding available, its pricing and the specific projects to be financed remain central details for assessing its potential development impact.
According to Environmental Finance, the bond is intended to finance affordable and sustainable housing in West Africa. Its denomination in West African CFA francs places the instrument within the region’s local currency financial system, a potentially important feature for housing markets where developers, households and financial institutions often face constraints in accessing long-term funding on manageable terms.
Housing finance remains a structural challenge across much of Africa. Rapid urbanisation, population growth and migration towards economic centres are increasing demand for homes and supporting infrastructure, while the supply of affordable formal housing frequently falls short of household needs. The challenge extends beyond the cost of construction to include access to land, secure tenure, transport, water, sanitation, electricity and mortgage finance.
In this context, development finance institutions can help mobilise capital for projects that commercial lenders may consider too risky or difficult to finance over long periods. A sustainability bond provides a mechanism for raising funds intended for eligible social and environmental purposes, potentially connecting investor capital with housing development objectives. The ultimate value of the instrument, however, will depend on the terms under which funds are raised and the projects they support.
The bond’s West African CFA franc denomination is particularly relevant to the region’s financing conditions. Where housing projects generate revenue in local currency but rely on foreign currency borrowing, exchange rate movements can increase debt-servicing costs and undermine project viability. Local currency funding can reduce that mismatch, although it does not eliminate interest rate risk, inflation, affordability constraints or the challenge of securing sufficiently long repayment periods.
The regional currency arrangement also gives the issuance a cross-border dimension. The West African CFA franc is used by countries in the West African Economic and Monetary Union, where common monetary institutions provide a shared framework for financial transactions. Yet housing markets across these countries differ in land administration, planning rules, construction costs, household incomes and the depth of domestic capital markets. A regional financing instrument will therefore need to accommodate different national conditions rather than assume that one housing model can be applied uniformly.
For households, the central test will be whether the financing supports homes that people can afford, rather than simply increasing the number of units built. Affordable housing depends on the relationship between selling prices or rents and household incomes, as well as access to transport and basic services. Projects located far from employment centres may offer lower construction costs but impose higher commuting expenses and reduce access to jobs, education and healthcare.
Environmental performance is another consideration. Housing construction requires substantial materials, land and energy, while poorly planned developments can increase transport emissions, place pressure on water supplies and expose residents to flooding or extreme heat. Investment in efficient building designs, appropriate materials, reliable water and sanitation systems, and climate-resilient infrastructure could reduce some of these risks over the lifetime of a development. Whether the bond will finance such measures, and how performance will be assessed, will depend on its eligibility criteria and reporting arrangements.
For investors, the credibility of a sustainability bond rests on more than its stated purpose. Clear rules on the allocation of proceeds, transparent reporting, and measurable social and environmental indicators help establish whether financing delivers the outcomes used to justify its sustainability designation. Relevant measures could include the number of homes financed, their affordability relative to local incomes, access to essential services, energy and water performance, and the resilience of developments to climate-related hazards. These are possible indicators for evaluating the programme, not disclosed commitments established by the available announcement.
The financing also raises questions about how the development bank will balance commercial discipline with its social mandate. Housing projects must generate sufficient revenue to service debt and attract capital, but higher returns can come into tension with affordability for lower-income households. Public authorities, developers and lenders will need to consider how land costs, infrastructure provision, subsidies and repayment structures affect the final price paid by residents.
The wider significance extends beyond West Africa. Across African economies, the ability to mobilise long-term capital for essential infrastructure and social investment is constrained by competing public spending needs and uneven access to finance. Instruments that draw on domestic and regional capital markets could help diversify funding sources, but they cannot replace effective urban planning, transparent land governance, adequate infrastructure budgets or policies that expand access to housing finance.
For Shelter Afrique Development Bank, the debut bond creates an opportunity to demonstrate how labelled financing can connect regional investment with measurable development outcomes. That assessment will require further disclosure on the amount raised, the cost of funding, the pipeline of eligible projects and the safeguards governing the use of proceeds. The available announcement does not establish these details or quantify the number of households expected to benefit.
The bond’s significance will ultimately be determined not by its designation as a sustainability instrument, but by whether it expands access to safe, affordable housing while improving the environmental performance of the built environment. For West African cities facing growing housing demand and infrastructure pressures, transparent allocation and credible impact reporting will be essential to establishing whether the financing delivers benefits beyond the capital markets.